APR Audit Services in India: CA Firm vs US CPA Firm vs Bank-Recommended Auditor, How to Decide
APR audit requirements for US, UK and overseas subsidiaries, including when an Indian CA is sufficient and when a local auditor is required for ODI.

Accorp Compliance Team
Our team of compliance experts specializes in PCI DSS, SOC 2, and other security frameworks to help businesses achieve and maintain compliance.
Every year around September, a finance head with a US or UK subsidiary asks the same question: who should do our APR audit? Three answers circulate. The Indian CA who signs the parent's books says "we'll handle it." The bank's relationship manager mentions "a firm we usually see." A US advisor says "you need a CPA."
All three can be right, depending on how the foreign entity is held. This guide explains how to decide before the 31 December deadline narrows your options.
What an APR Audit Actually Involves
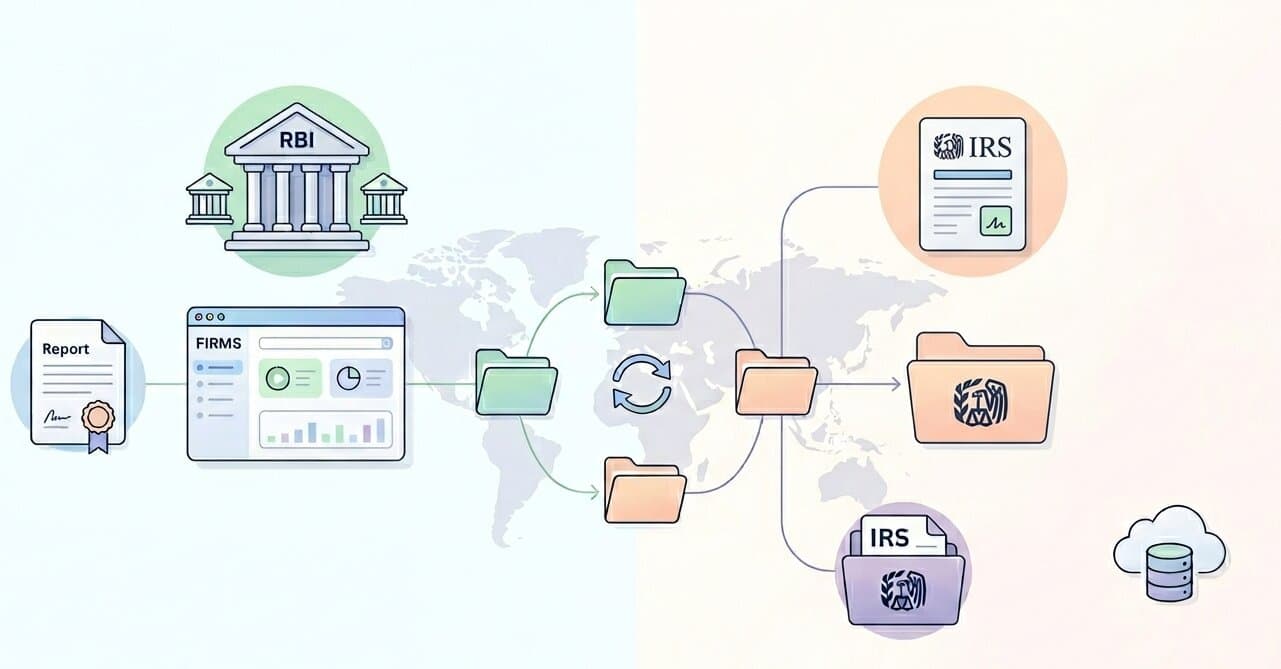
An APR audit is the audit or professional certification of the financial statements that support your Annual Performance Report. The report goes to the RBI through your Authorised Dealer (AD) bank, and it is the main recurring step in ODI compliance. Every Indian party holding overseas direct investment has to file one for each foreign entity, whatever its size or profitability.
The financials behind the filing are central. Where the Indian investor holds 10% or more with control, the report is generally based on the foreign entity's audited accounts. In narrower situations, the rules allow unaudited statements certified by an Indian auditor. Rules and AD bank practice evolve, so confirm the current direction before you commit to a route.
This is why the auditor choice matters. A mismatch between the entity's profile and the auditor's credentials is the most common reason the bank returns a package.
Option 1: An Indian CA Firm
An Indian chartered accountant is the natural first call. They know your parent company, your ledgers and your bank, and they understand RBI reporting requirements from the Indian side.
Where a CA works well
Certification of unaudited statements, where the rules permit that route
Reconciling the Indian parent's investment records with the figures in the report
Handling the Indian-side paperwork, such as the certificate format and the AD bank submission
Where a CA runs into limits
A CA is licensed in India. Issuing an audit opinion on a Delaware corporation's accounts under US auditing standards falls outside that licence.
Where host-country law requires a statutory audit, or you control the entity, the opinion has to come from a qualified local professional.
A CA is the right lead for the Indian filing. For the audit of the foreign subsidiary of an Indian company, a CA alone is often not enough.
Option 2: A US CPA or Other Host-Country Firm
If your subsidiary is a US C-corp or LLC, a UK Ltd or a Singapore Pte Ltd, a firm licensed in that country can issue the audit opinion under local standards. That means a CPA for US entities, an ICAEW or ACCA member for UK ones, and an ISCA-registered auditor for Singapore.
The strength is acceptance. An AD bank reading a CPA-signed audit report on US GAAP financials is looking at a document it can place immediately.
The weakness is context. A US firm may know GAAP and AICPA standards thoroughly and have never seen Form ODI Part II. Their report can be technically perfect and still miss what the AD bank wants: the UIN, the currency presentation, the certificate wording or the reconciliation to the filing.
For foreign investment reporting, ask a host-country firm whether it has supported an Indian filer before. If not, budget time for your CA to bridge the gap.
Option 3: The Bank-Recommended Auditor
Banks often suggest someone, and the suggestion can be useful. A firm that has dealt with that branch knows its checklist, its preferred format and its turnaround.
Still, a recommendation is not a requirement. In general, the rules look at an auditor's qualification, not their relationship with the bank. Treat the suggestion as information about the bank's habits, not as a rule. Two cautions:
Fit: Recommended firms are usually Indian practices. They may be excellent at certification and still unable to sign an audit opinion for a foreign entity.
Independence and price: A referral is not a competitive quote. Compare at least one alternative.
Ask the bank in writing what it requires from the auditor, rather than whom it prefers.
Side-by-Side Comparison
Factor | Indian CA firm | US/UK/Singapore firm | Bank-suggested auditor |
Can sign a foreign audit opinion | No | Yes | Depends on licence |
Knows ODI reporting | Strong | Varies | Strong at that branch |
Best for | Unaudited or certified cases, Indian reconciliation | Controlled entities needing a statutory-grade audit | Smooth routing at your bank |
Main risk | Rejection when a host-country audit is needed | Report ignores RBI formatting | Limited options, little price comparison |
A Simple Way to Decide
Work through these questions in order:
Do you control the foreign entity, with 10% or more equity? If yes, plan on a host-country audit.
Does local law already require a statutory audit? If yes, use that audit as the base and make sure the report suits RBI reporting.
Is the entity small, exempt locally or non-controlled? Check whether certified unaudited accounts are acceptable for your case, and ask your CA to confirm.
Is the entity dormant or loss-making? The filing obligation still exists, so do not treat this as a reason to skip the audit question.
Does the entity have step-down subsidiaries? Each reportable entity needs its own treatment, so scope the engagement before pricing it.
Many groups end up with a hybrid: a host-country firm signs the audit, and the Indian CA handles certification, reconciliation and the bank file. That is not duplication, because each professional covers what the other cannot.
Mistakes That Cause Rejections
Starting in November. Overseas auditors typically need weeks, and holiday periods in the US and UK compress the schedule further.
Mismatched numbers. Figures in the report must tie exactly to the audited statements, including the INR conversion.
Wrong accounting framework. Statements prepared under Indian standards for a US entity create avoidable queries.
Unsigned or unstamped pages. Banks are strict on signatures and certificate format.
Ignoring earlier years. Pending APRs from prior years can hold up the current one and future overseas investment compliance.
Cost and Timing
Fees depend on the jurisdiction, the entity's complexity, the quality of its books and how close to the deadline you engage. A clean, repeat engagement costs noticeably less than a first-time audit of messy records. Whatever the quote, ask what it includes: audit only, or also the certificate, the reconciliation and the bank follow-up.
Working backwards from 31 December is a reasonable discipline: books closed and reconciled by September, auditor engaged by early October, draft audit by mid-November, and the AD bank submission with time left for queries.
Final Thoughts
Think of the decision in terms of roles, not brands. The Indian CA understands your parents and your bank. The host-country auditor holds the licence the foreign entity requires. The bank defines the format. Choose the combination your ownership structure requires, confirm it with your AD bank early, and APR becomes routine FEMA compliance instead of a December scramble.
Need help with APR audit and compliance? Visit our service page to learn more.
Frequently Asked Questions
1. Can the same firm do both the Indian and foreign work?
Only if it holds the right licences in both places. Otherwise, expect two professionals.
2. Is an Indian CA certificate ever enough?
In specific situations the rules allow certified unaudited statements. Do not assume your case qualifies without checking.
3. Does a missed APR change the auditor decision?
Yes. Back-year filings may need audited accounts for each missed year, which affects timing and scope.
4. Does my AD bank have to approve the auditor first?
Generally no, since the rules look at qualification, not a pre-approved list. Still, ask the branch in writing what it expects from the report and certificate to avoid queries later.
5. Can I change auditors mid-cycle?
You can, but it costs time. A new auditor needs weeks to review opening balances and build working papers, so switch before November or risk missing 31 December.