Draft FEM (Foreign Investment) Rules 2026: What ODI Reporters Should Watch
RBI's 2026 draft Foreign Investment Rules explained, including its impact on APR, FLA, foreign-owned Indian companies, ODI structures, and FEMA compliance.

Accorp Compliance Team
Our team of compliance experts specializes in PCI DSS, SOC 2, and other security frameworks to help businesses achieve and maintain compliance.
If you file Annual Performance Reports for a foreign subsidiary, the July 2026 draft rules from RBI may look like someone else's problem. The headline is "foreign investment," and your world is overseas investment. Mostly you're right. But promoters with cross-border structures should still read the draft closely, because the two regimes meet more often than people expect.
The short answer: APR is not being rewritten
On 21 July 2026, RBI released the draft Foreign Exchange Management (Foreign Investment) Rules, 2026 for public consultation, with comments invited until 31 August 2026. The draft would replace the Non-Debt Instruments (NDI) Rules, 2019, which govern investment into India by people resident outside India. Overseas investment by Indian residents falls under a separate set of rules, the Overseas Investment Rules, 2022, and nothing in the analyses I reviewed proposes changing them.
So the APR stays where it is. For APR filing India, that means:
The report is still due by 31 December for each foreign entity.
It is still based on audited statements of the foreign entity where you hold control.
The late submission fee route still applies.
If your only exposure is an Indian company with a subsidiary abroad, the draft changes nothing for your annual cycle. The rest of this piece is for people whose structures touch both sides.
What the draft actually proposes
In plain terms, the draft would:
Redefine the subject. Instead of "non-debt instruments," the rules would apply to foreign investment in the equity of an "eligible investee entity."
Fold indirect investment into the main definition. Foreign investment would include investment made indirectly through a "foreign controlled entity" (FCE), replacing much of the separate downstream-investment regime.
Simplify FDI versus portfolio investment. Commentators read the draft as treating foreign investments of 10% or more in an entity as FDI, with a single threshold for listed and unlisted companies.
Place the compliance burden on the parties. The investor and the investee entity, or the transferor and transferee, carry the responsibility.
Replace FOCC with FCE. The old "foreign owned and controlled company" test gives way to a control-based concept, where control means the right to appoint a majority of directors or to control management.
This sits alongside a separate change: an amendment to the NDI Rules, notified on 2 May 2026, which added requirements for investments from border countries.
Where your structure may touch the draft
Foreign promoters and flipped structures
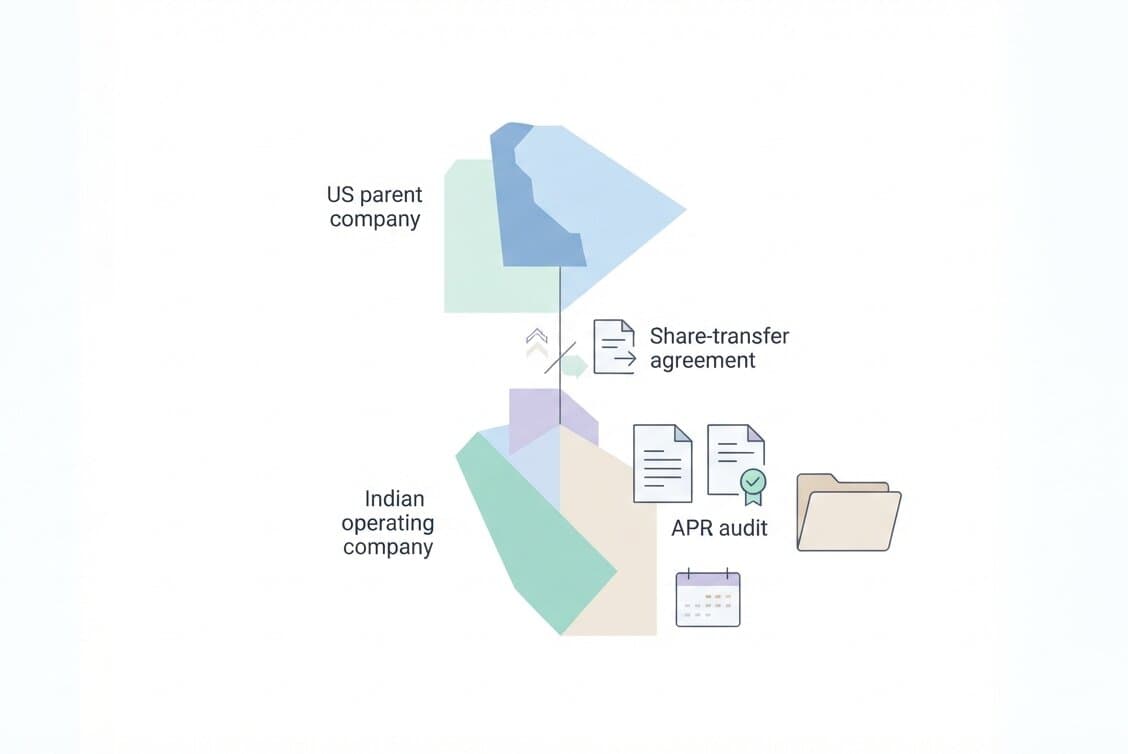
A common founder structure is a US parent that owns an Indian operating company, which is the Delaware-flip pattern. The founder reports the US parent through APR as an overseas investment, while the Indian operating company is receiving foreign investment, which falls under the NDI regime and, once notified, the new rules. The same family of facts therefore sits under both frameworks at once. If the draft's control test changes who counts as foreign-controlled, the Indian company's own status may shift even though the founder's APR doesn't.
Round-tripping and layered holdings
Because the draft counts investment through an FCE or through persons under common control, structures where money leaves India and comes back through a chain deserve a fresh look. Under the overseas investment framework, layers of subsidiaries are already restricted, so adding a new inbound test creates another question to ask about any structure where capital makes a loop. The draft does not say how these cases will be treated, so treat this as a question to ask and not an answer to rely on.
The control threshold
Commentators have flagged that the draft links control to a 10% voting-rights trigger and that this may complicate structuring. If the final text keeps something like it, entities with modest foreign voting rights may suddenly fall into the foreign-controlled category and, with it, into sector-specific conditions. If you hold or advise on such an entity, this is the provision to follow most closely.
What reporting could change
This is the part least settled. Commentary on the draft says it is yet to be seen how reporting for indirect and downstream investment would work once direct and indirect investment sit in one definition. Under the current regime, the familiar filings are Form FC-GPR, Form FC-TRS and the annual FLA return, due 15 July. Separately, the border-country rules contemplate additional disclosures in a format that DPIIT is to prescribe.
Two practical points follow for subsidiary compliance reporting:
Your FLA return and your APR describe the same group from different sides. Keep their numbers consistent.
The draft puts responsibility on both investor and investee. Make sure your group knows who owns each filing, because shared responsibility tends to fall between two desks.
What hasn't been carried over
The draft, as currently written, does not reproduce certain downstream-investment requirements from the earlier regime, such as the restriction on source of funds and the auditor certificate for the first-level Indian company. Legal commentary describes the draft as concise, but that brevity leaves several questions open, and the final text may add clarifications.
Draft versus final: where things stand
As of 1 October 2026, the comment window has closed. I found no notification of final rules, so treat everything above as proposed. Provisions can change between draft and final text, and RBI's final rules are issued through the Ministry of Finance, so check the Gazette before acting on any specific provision.
A practical watch list for ODI reporters
Question to ask | Why it matters |
Does any foreign person hold shares or voting rights in my Indian entity? | You may sit under both inbound and overseas rules |
Does capital leave India and return through a subsidiary chain? | Indirect-investment definitions may apply |
Does the group have a clear owner for FC-GPR, FLA and APR? | The draft stresses shared responsibility |
Is my foreign subsidiary audited by a locally licensed auditor? | The audit of a foreign subsidiary of an Indian company remains the basis for APR |
Have I read the final notification, not just summaries? | Draft text can change |
What to do now
Keep filing on the existing timetable. Nothing in the draft suspends an APR, an FLA or an audit.
Map your structure on one page. Show each foreign subsidiary company, each foreign shareholder in Indian entities, and each loop of capital.
Tell your auditors and advisers. They can flag whether a future definition would change your status.
Wait for the final text before restructuring. Changing a structure to fit a draft is risky.
Frequently asked questions
1. Does the draft change the APR due date?
No. The APR is part of the overseas investment framework, which this draft does not amend.
2. Is the draft in force?
No. It was released for consultation, and I found no final notification.
3. Who is affected most?
Indian companies with foreign shareholders and foreign-parent structures, such as flipped startups.
4. Do I need new FEMA compliance steps today?
Not because of the draft. Follow the rules currently in force.