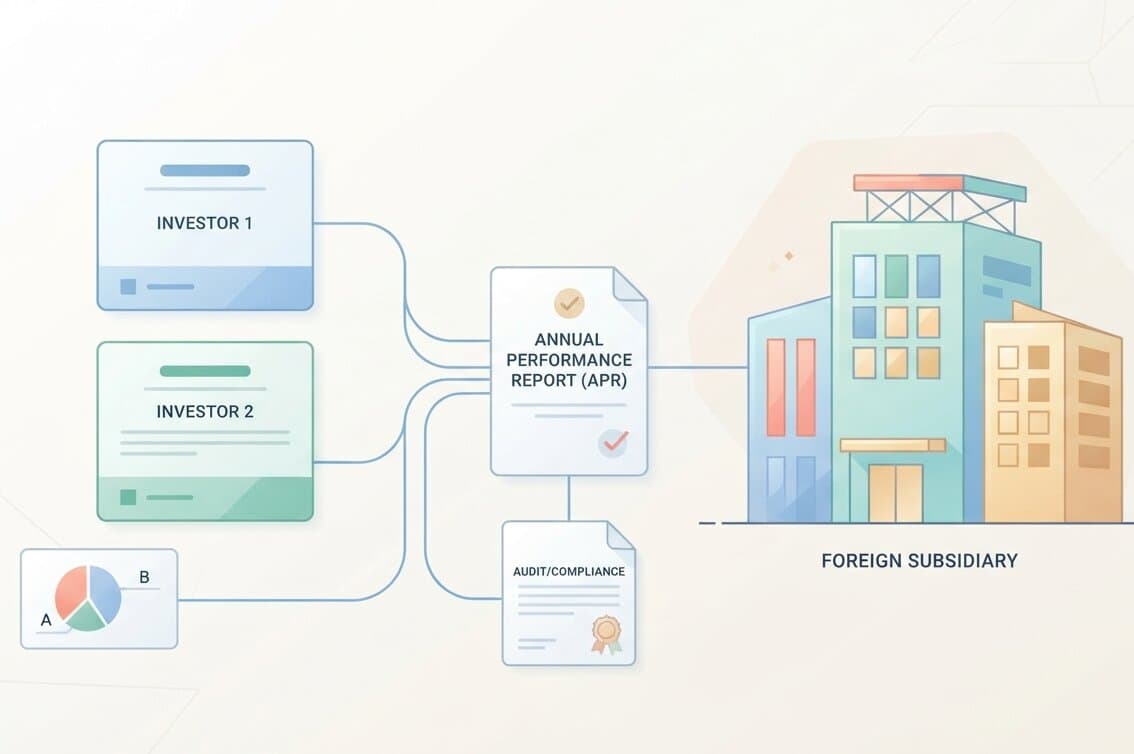
APR for GIFT City / IFSC Entities (verify the current RBI position first)
Understand APR and ODI compliance for GIFT City IFSC investments, including audit rules, FLA reporting, AD bank filing, timelines, and late fees.

Accorp Compliance Team
Our team of compliance experts specializes in PCI DSS, SOC 2, and other security frameworks to help businesses achieve and maintain compliance.
GIFT City is a short drive from Ahmedabad. For FEMA purposes, an Indian company that puts money into a company there has still made an overseas investment. Founders find this odd, and it is the reason a surprising number of IFSC-linked structures miss a filing that was never on their calendar.
Why an entity in Gujarat can be a "foreign entity"
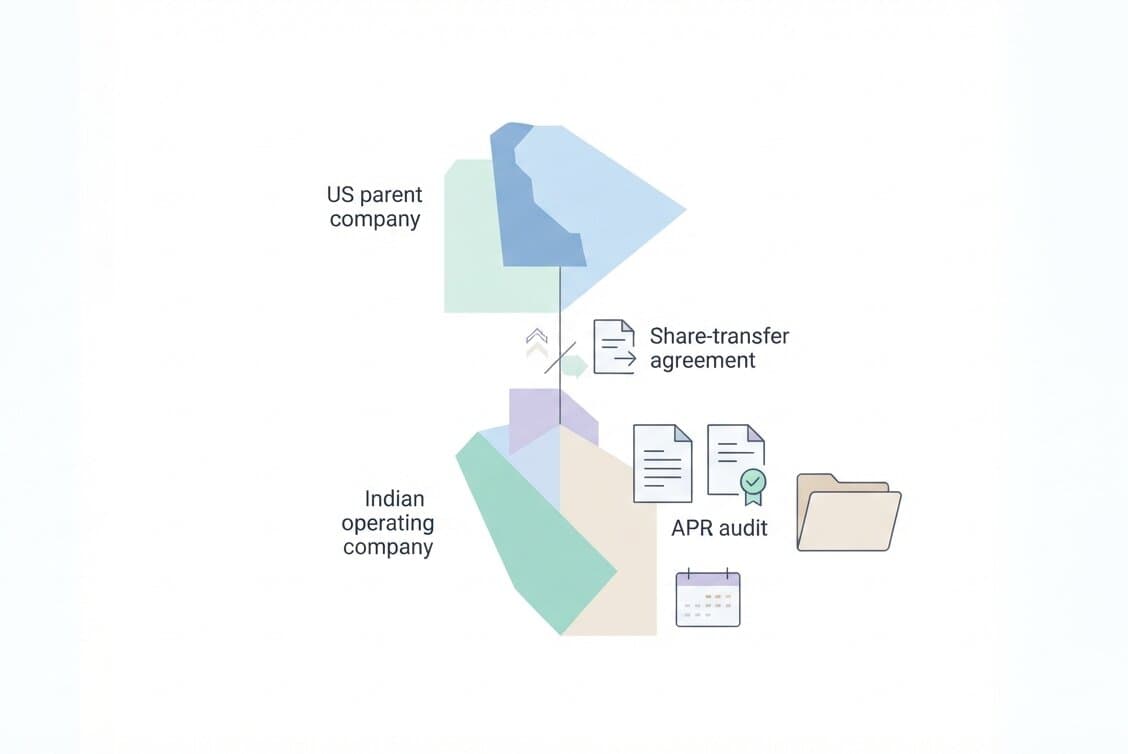
The Overseas Investment Rules, 2022 define a foreign entity as one formed, registered or incorporated outside India, and they expressly bring in entities incorporated in an International Financial Services Centre (IFSC) with limited liability, including investment funds or vehicles. GIFT City is the IFSC in practice. So when an Indian party takes unlisted equity in an IFSC company, the investment is treated like a stake in a subsidiary abroad, with all the overseas investment compliance that goes with it.
Geography does not decide this. The legal character of the entity does. That is why IFSC investments get a separate chapter in the framework instead of being folded into ordinary domestic investment.
Who can invest, and with what limits
Indian entities (companies, LLPs and registered partnership firms) and resident individuals can invest in IFSC entities, subject to the conditions set out in the Rules. Two points deserve attention:
Resident individuals face a structural restriction. An individual who controls an IFSC entity cannot do so if that entity has a subsidiary or step-down subsidiary outside the IFSC. Keep an IFSC vehicle clean if you hold it personally.
Financial services need extra care. Indian entities not in financial services may invest in an IFSC entity that is itself in financial services, but regulatory clearances and eligibility conditions may apply. Check the position with your adviser before funding the entity, not afterwards.
These rules shape ODI compliance from day one, since the original structure determines what you must report every year.
So does APR filing in India apply to IFSC investments?
Yes. The Annual Performance Report is a yearly return for each foreign entity in which a person resident in India holds overseas direct investment. Because an IFSC entity falls within that definition, the obligation follows. Practitioner summaries of the framework state that resident individuals making ODI must file an APR by 31 December each year, and nothing in the same material suggests an IFSC carve-out.
That means:
One APR for each IFSC entity, every year, until you exit completely.
Filing through your authorised dealer (AD) bank before 31 December.
Details of capital structure, turnover, profit or loss, net worth, dividends and any step-down subsidiaries.
A nil-activity or loss-making IFSC vehicle does not change this. The form is triggered by the investment, not the performance.
The audit: who signs when the subsidiary is in India's own IFSC
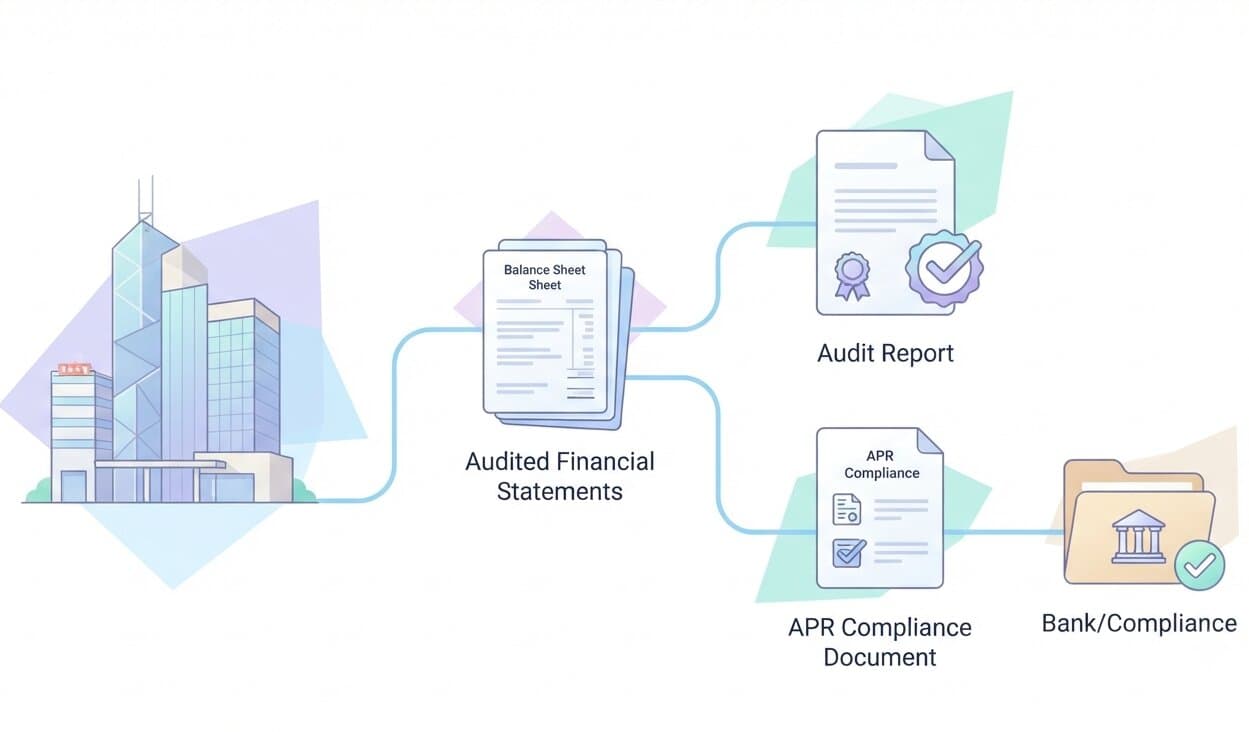
Here the usual APR advice flips. For a Hong Kong or US subsidiary, an Indian CA cannot sign, because the audit must come from a licensed local professional. An IFSC company is incorporated under Indian law and audited by whoever its governing framework requires, so the signer is generally the statutory auditor appointed under that framework, which is typically an Indian chartered accountant or firm.
That makes the audit of a foreign subsidiary of an Indian company look different here from other jurisdictions:
The statutory auditor's report on the IFSC entity is the natural base document for the APR.
Where the Indian investor has control, the APR is still to be based on audited statements, even if the host framework did not require an audit. The unaudited route is only open where there is no control.
IFSCA-regulated activities may carry their own auditor eligibility and independence conditions, such as peer-review status or a limit on consecutive appointment years. These apply on top of the APR.
Treat this as a reasoned reading of the framework, not a published RBI ruling on IFSC auditors. Confirm with your AD bank which signatory it expects.
Reporting currency and form mechanics
Many IFSC units keep their books in a foreign currency, usually US dollars. The APR asks for all figures in a single foreign currency, so a USD ledger is a convenience, not a problem. Prepare the report in the currency of the audited statements, and keep every figure identical to the signed report. The usual APR hygiene still applies: the same UIN throughout, actual amounts rather than rounded ones, and a single filer when several Indian investors are involved.
Don't confuse APR with FLA, especially in 2026
The IFSC world changed on another front this year. According to a July 2026 law-firm note, IFSCA clarified by press release on 1 July 2026 that IFSC entities should follow IFSCA's own instructions on FLA reporting. Where an Indian resident entity invests in an IFSCA-regulated entity, it still reports that investment to RBI as ODI in its own FLA return, but the IFSC entity itself is not required to file the FLA with RBI.
This is a separate matter from the APR. The FLA is due on 15 July, and the APR on 31 December. Do not assume the FLA relaxation reduces your APR duty. Read the IFSCA press release and your bank's instructions directly before relying on this, since it is recent and still working its way through bank practice.
A realistic timeline
Stage | What to do |
Within the year | Report each tranche of investment on time |
Year-end | Close the books; confirm the audit calendar |
By October | Request signed statements and the auditor's report |
November | Prepare the form and reconcile it to the report |
By 31 December | Submit through the AD bank and keep the acknowledgement |
Where IFSC investors slip
Assuming domestic means are exempt. The Indian address misleads people into skipping the filing.
Mixing up FLA and APR. One is on 15 July, the other on 31 December, and they have different rules.
Funding before checking eligibility. Investment structure and the financial-services question come before the money moves.
Skipping step-down disclosures. A subsidiary under the IFSC entity must be reported.
Relying on an unaudited basis. If you hold control, plan for audited statements.
What a miss can cost
A late APR can be regularised by paying a flat late submission fee of ₹7,500 per return, if you opt for it within three years of the due date. Beyond that, compounding is slower and more expensive. Banks can also hold up outward remittances and fresh overseas investments until the record is clean.
Frequently asked questions
1. Is an IFSC entity really a foreign subsidiary company?
For the Overseas Investment Rules, yes, if it is a limited-liability entity formed in the IFSC.
2. Does a dormant IFSC vehicle still need an APR?
Yes. The obligation depends on the investment, not on activity.
3. Can an Indian CA sign the audit?
The statutory auditor is appointed under the entity's own framework, which is often an Indian CA firm. Confirm with your bank.
4. Who files if two Indian investors share one IFSC entity?
The larger shareholder files, or the investors designate one filer by undertaking.