Equal Stakes, One APR: How Two Indian Investors File Jointly or Authorise a Single Filer
Who files APR when Indian investors jointly own a foreign entity? Understand highest stake, equal-stake options, documentation, and APR audit rules.

Accorp Compliance Team
Our team of compliance experts specializes in PCI DSS, SOC 2, and other security frameworks to help businesses achieve and maintain compliance.
"Two of us own the company. So who files the APR?" The question comes up the first time two Indian investors share a foreign entity. The answer sits in one short instruction on the RBI's own APR form, and most finance teams never read it.
Get it wrong and nobody files, because each side assumes the other has it covered. That is how a routine annual return becomes a FEMA compliance problem. This guide covers the rule and how "highest stake" is worked out. It also covers the two options when stakes are equal, how to document the arrangement, and where the APR audit fits.
What the RBI instruction says
Every resident who makes overseas direct investment in a foreign entity must report on it each year. Where more than one resident has invested in the same entity, Instruction 4 to the APR form settles who does the filing. The resident holding the highest stake files. If holdings are equal, the APR may be filed jointly. The form adds that the investors can either file together or authorise one of them to file for all.
This is a rule about responsibility, not about splitting the report. There is one APR for each foreign entity, filed through the designated AD bank by 31 December, and not one APR per investor. Under the RBI reporting requirements, the filer answers for the whole document.
Working out the "highest stake"
The test compares each Indian investor's own shareholding in the foreign entity. Here are three common patterns:
Indian holdings | Foreign partner | Who files |
Company A 40%, Company B 35% | 25% | Company A, as the highest stake |
Company A 30%, Company B 30% | 40% | Equal: file jointly or authorise one |
Company A 26%, resident individual 24% | 50% | Company A |
One detail catches people out. The capital structure paragraph of the form (Instruction 7) shows the total stake of all Indian residents combined, and it is cumulative. In the first row the APR would show 75% Indian, even though Company A holds 40%. The form reports the combined Indian holding, while the highest-stake test picks the filer.
The instructions do not say whether two related investors, such as a parent and its promoter, are treated together. Ask your AD bank before you assume either answer.
Equal stakes: two ways to handle it
Option one: file jointly. Both investors file the same APR together. It keeps both sides visibly involved, and it works when the two are equal partners who watch each other closely. The cost is coordination, since two boards, two sets of authorised signatories and possibly two AD banks have to move in step. Ask how your bank wants the signature blocks handled before you start.
Option two: authorise one filer. One investor is authorised by the other to file for both. It is usually the more practical route, with one owner and one timeline. Pick the investor with the stronger finance team, or the one whose AD bank relationship is easier.
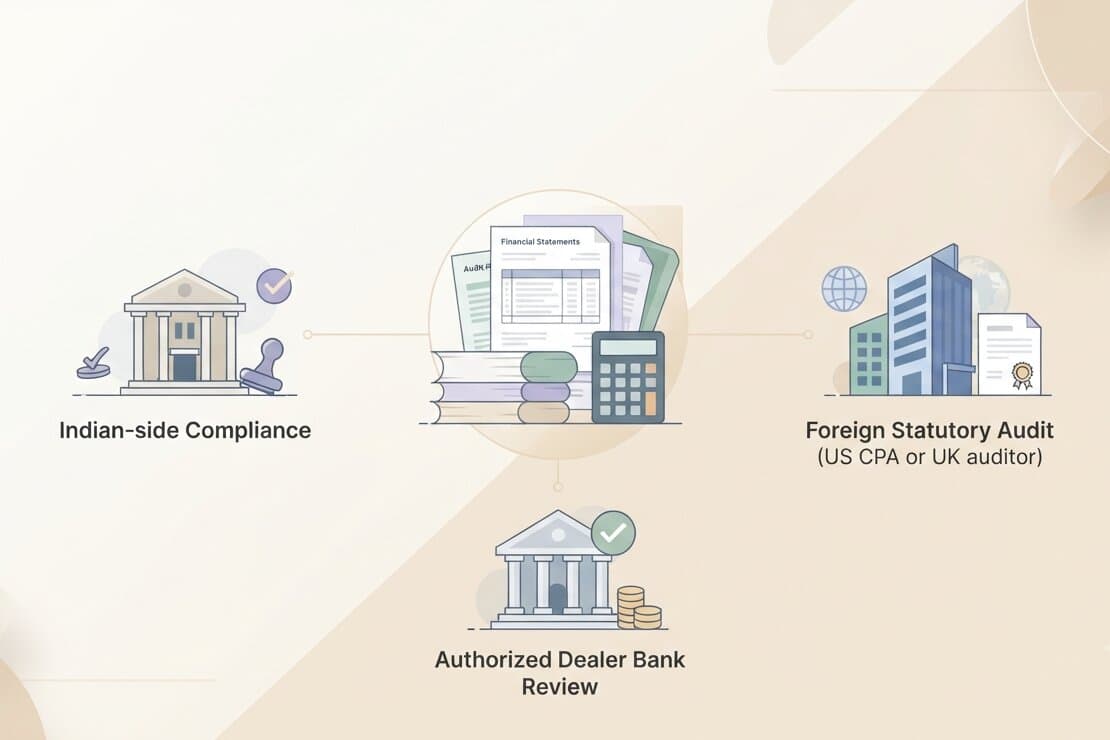
Choosing the filer also determines whose auditor signs. The auditor block on the form belongs to the filing investor's statutory auditor, or a chartered accountant where the investor is an individual. So decide the filer before the audit starts, not after.
What the filer takes on
Being the filer means owning more than the submission:
The history. The form asks the filer to confirm that all earlier APRs for the entity have been filed. If the nominated investor has a gap in its record, it holds up the current filing for everyone. Our note on missed APRs explains the knock-on effects.
The changes. Shareholding changes during the year must be reported, and under Instruction 5, leaving them out counts as not submitting the APR at all.
The control answer. Paragraph IV asks whether the filing investor has control, and that answer decides whether unaudited accounts are ever possible. Two investors acting together under an agreement can have control between them, so read our guide on what counts as control.
The APR audit in a jointly owned company
Instruction 3 makes audited financial statements of the foreign entity the default basis. The exception needs both no control and no audit mandate in the host country. In a jointly owned foreign subsidiary company, that leaves the audit question open to argument, so treat an audit as the working assumption.
One audit of the entity serves the APR for every Indian investor. Nobody needs a second one. The practical work is agreeing who instructs the auditor, how the fee is split, who receives the report, and who chases the books.
That last point matters most when the foreign partner runs the accounts. Check the shareholders' agreement for information rights, because an audit of a foreign subsidiary of an Indian company depends on getting records on time. Our post on APR for joint ventures covers that side, and the APR audit page explains how the audit itself runs.
Putting the arrangement in writing
Whichever route you choose, a short authorisation note protects both sides. It should cover:
the foreign entity, and the UIN each investor holds;
the years it covers, whether one year or a standing arrangement;
who signs, and which board approvals are needed on each side;
a date by which final accounts must reach the filer, well before 31 December;
how audit costs and any late-submission fee would be shared; and
what happens if the filer sells down, changes AD bank or leaves the structure.
Where these arrangements go wrong
Nobody files. Each investor assumes the other has it. A late APR carries a flat late submission fee of ₹7,500 per return, available for up to three years, after which compounding is needed. Banks have also been reported to hold back further overseas remittances until pending APRs are cleared.
Stakes shift. A capital top-up by one investor can make it the highest holder, and the responsible filer changes with it. Recheck the position every year, especially after new funding.
Responsibility is unclear. The form's instructions do not say how responsibility is shared if the nominated filer misses the deadline. Until your bank tells you otherwise, treat it as a shared risk and write down who diaries the date.
The rule is short, but it only works if someone owns it. Decide before the first of December, record the decision, and put a yearly recheck in the calendar for the whole life of the ODI compliance file.