Can a Remote/Virtual Audit Satisfy RBI's Requirement — or Does the Auditor Need to Be On the Ground?
APR audit for overseas subsidiaries: see if physical visits are required, how remote verification works, evidence needed, FEMA compliance, and RBI rules.

Accorp Compliance Team
Our team of compliance experts specializes in PCI DSS, SOC 2, and other security frameworks to help businesses achieve and maintain compliance.
For Indian companies with overseas subsidiaries or joint ventures, the Annual Performance Report (APR) is often treated as a routine yearly filing. In reality, it sits at the intersection of overseas investment compliance, FEMA compliance, financial reporting and audit evidence.
One practical question comes up repeatedly: Does the auditor have to physically visit the overseas subsidiary, or can the audit and supporting verification be completed remotely?
The short answer is that RBI's overseas investment framework does not prescribe a blanket requirement that the auditor must physically travel to the foreign entity's premises merely for APR purposes. The focus is on whether the APR is prepared using the appropriate financial statements and whether the required certification is provided by the appropriate professional. The exact audit procedures, however, remain subject to applicable auditing standards, the host country's law, the auditor's professional obligations and the facts of the engagement.
That distinction matters. A virtual audit can be perfectly workable in many cases, but "remote" does not mean "less rigorous." If the auditor cannot obtain sufficient appropriate evidence remotely, an in-person procedure may still become necessary.
This guide explains how the requirement works and what Indian companies should prepare before their next APR audit.
What Is the APR and Why Does the Auditor Matter?
An Annual Performance Report is part of India's reporting framework for overseas direct investment (ODI). Under the current Overseas Investment Regulations, a person resident in India that has made ODI is generally required to submit an APR for each foreign entity every year, subject to specified exceptions. The APR is generally due by 31 December, although a different timing applies where the foreign entity's accounting year ends on 31 December.
The APR captures information about the overseas entity and its performance, including matters such as its financial position, investment and changes in the overseas structure.
The regulatory framework also establishes an important evidence principle: the APR should generally be based on the audited financial statements of the foreign entity. Where the Indian investor does not have control and the foreign jurisdiction does not mandate an audit, unaudited financial statements may be used if they are appropriately certified by the statutory auditor of the Indian entity or, where applicable, a chartered accountant.
So the key question isn't simply:
"Did the auditor physically visit the overseas company?"
The more relevant questions are:
Were the appropriate financial statements obtained?
Were they audited where required?
Can the auditor obtain sufficient evidence?
Are the APR figures consistent with the underlying records?
Have changes in shareholding, step-down subsidiaries or restructuring been properly reported?
Has the required certification been completed?
Does RBI Specifically Require an On-Site Audit?
The current RBI Overseas Investment Directions require overseas investment reporting to be made through the designated Authorised Dealer (AD) bank and state that the APR is to be certified by a chartered accountant where statutory audit is not applicable. The Directions do not state that the auditor must physically travel to the foreign subsidiary's premises to conduct the APR-related work.
This is an important distinction because companies sometimes confuse three separate things:
The foreign entity's statutory audit
The Indian investor's APR preparation and certification
Additional verification performed by an auditor or professional
These are not necessarily the same engagement.
If the overseas subsidiary is legally required to have its financial statements audited under the law of its jurisdiction, those audited financial statements are generally the starting point for the APR.
The Indian company should not assume that it needs to commission an entirely new physical audit merely because an APR must be filed.
When Can a Remote Audit Work?
A remote or hybrid audit can work where the auditor can obtain sufficient appropriate evidence without being physically present.
Modern audit procedures already allow auditors to work with electronic accounting systems, cloud-based records, video meetings, electronic confirmations and digital document repositories. The question is whether those procedures provide enough reliable evidence for the particular audit conclusion.
For an overseas subsidiary, a remote process may involve:
Secure access to accounting records
Digital copies of financial statements
General ledger and trial balance extracts
Bank statements and reconciliations
Intercompany transaction schedules
Fixed-asset registers
Corporate documents
Shareholding records
Tax filings
Management representations
Board minutes
Contracts and invoices
Electronic confirmations from banks or counterparties
Video walkthroughs of relevant processes or assets
For a relatively straightforward subsidiary with clean accounting records, a stable ownership structure and good digital documentation, this may be sufficient.
But the auditor — not the company — ultimately determines whether the evidence obtained is adequate for the engagement.
Remote Does Not Mean "Document Review Only"
This is where companies sometimes make a mistake.
A virtual audit should not become a process where management simply uploads documents and expects the auditor to sign the APR. Auditors still need to evaluate whether the information is reliable and whether there are inconsistencies that require investigation.
For example, suppose an overseas subsidiary reports that it owns a manufacturing facility worth $10 million. If the auditor has questions about the asset's existence, valuation or ownership, simply receiving a scanned fixed-asset register may not be enough.
The auditor could instead request:
Purchase documentation
Title or ownership records
Depreciation schedules
Insurance documents
Photographic or video evidence
Third-party confirmations
Physical inspection where necessary
The final procedure depends on the auditor's assessment of risk.
What Happens When the Foreign Subsidiary Has a Local Statutory Auditor?
This is one of the easiest situations to handle. If the overseas subsidiary is subject to mandatory audit in its jurisdiction, the Indian company should obtain the final audited financial statements and retain the relevant audit documentation and corporate records. The local auditor's work provides the financial reporting foundation for the APR.
However, this does not mean the Indian company can simply forward the financial statements to its AD bank without checking anything else.
The company should reconcile the APR information against:
The subsidiary's audited financial statements
The original ODI investment information
Shareholding records
Previous APR filings
Subsequent investments
Loans and guarantees
Step-down subsidiaries
Changes in ownership
Disinvestment or restructuring transactions
The current regulations specifically require reporting of certain changes involving acquisition, setting up or winding up of step-down subsidiaries and alterations in the foreign entity's shareholding pattern through the APR.
What If the Overseas Country Does Not Require an Audit?
This is where the rules become particularly useful.
The regulations provide an alternative for situations where the Indian investor does not have control over the foreign entity and the host jurisdiction does not mandate an audit of its books.
In such circumstances, the APR can be based on unaudited financial statements, provided those statements are certified as unaudited by the statutory auditor of the Indian entity or by a chartered accountant where statutory audit is not applicable.
The practical takeaway is important:
An overseas entity not being subject to mandatory statutory audit does not automatically eliminate APR reporting.
Instead, the regulatory framework provides a mechanism for using appropriately certified unaudited accounts in qualifying circumstances.
Companies should therefore determine early whether the foreign entity:
Is legally required to undergo an audit;
Is controlled by the Indian investor;
Has an accounting year different from India;
Has undergone any ownership or structural changes; and
Falls within an APR exemption.
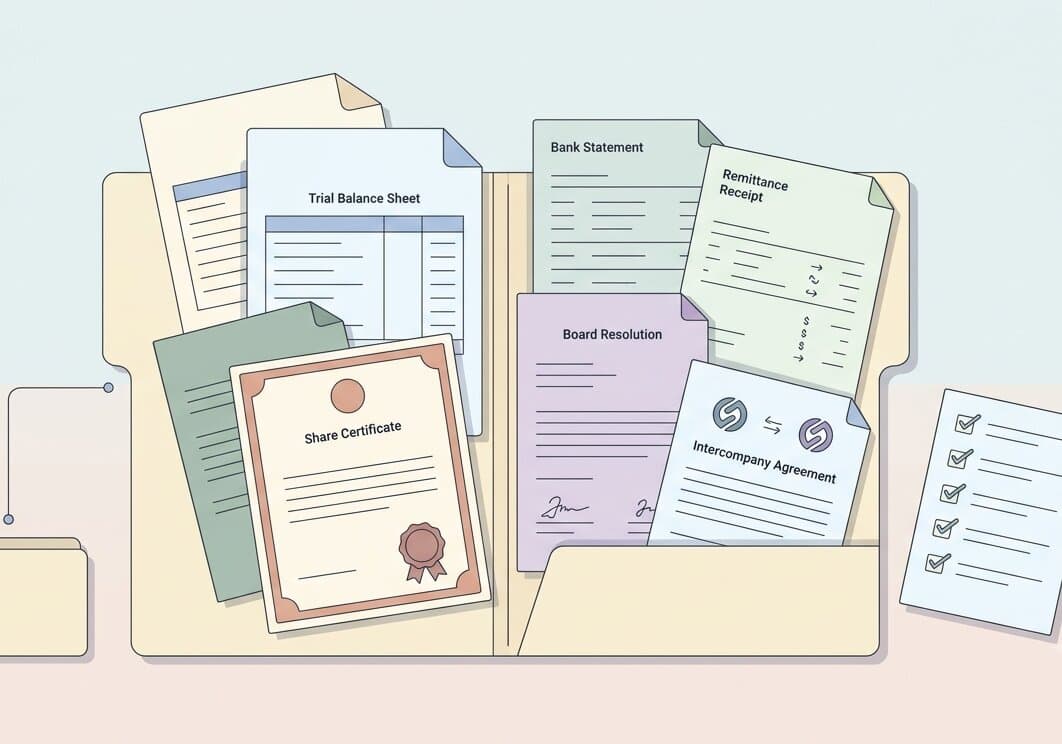
What Evidence Should Be Prepared for a Remote APR Audit?
A well-organised evidence pack can make a remote engagement substantially easier.
1. Final Financial Statements
Keep the latest audited financial statements of the overseas entity, or certified unaudited financial statements where the applicable exception permits their use.
2. Ownership Documents
Prepare:
Share certificates or equivalent evidence
Shareholder registers
Capitalisation tables
Details of changes in ownership
Details of additional investments
This is particularly important where the overseas entity has issued new shares during the year.
3. ODI and AD Bank Records
Keep copies of the relevant ODI reporting, remittance records and correspondence with the designated AD bank.
The current RBI framework routes overseas investment reporting through the designated AD bank. Incomplete reporting can be treated as non-submission.
4. Step-Down Subsidiary Information
If the overseas entity established, acquired, transferred or closed a step-down subsidiary during the reporting period, maintain the relevant corporate and financial documentation.
5. Intercompany Transactions
Where the Indian company and overseas subsidiary transact with each other, maintain:
Agreements
Invoices
Loan documentation
Interest calculations
Royalty arrangements
Management-fee records
Reconciliation statements
These documents can become important where the auditor is assessing whether the financial information reported in the APR is consistent with the underlying records.
What Can Make a Remote Audit Difficult?
Remote auditing becomes less straightforward when evidence is difficult to verify electronically.
Common problem areas include:
Poorly maintained overseas records
If accounting records are incomplete, a remote audit can actually take longer because the auditor has to request additional evidence repeatedly.
Significant cash transactions
Cash-heavy operations may require stronger verification procedures than a digitally documented business.
Physical assets
Property, plant and equipment, inventory and other physical assets may require additional procedures if documentary evidence alone isn't sufficient.
Complex ownership structures
Multiple subsidiaries, trusts, holding companies or cross-border investments can make it harder to establish exactly who owns what.
Unusual related-party transactions
Large loans, guarantees, royalty arrangements or transfers between group companies may trigger additional questions.
Prior-year discrepancies
If the current year's numbers don't reconcile with the previous APR or financial statements, the auditor may need to investigate before certification.
Does the Auditor Need to Be in the Same Country as the Subsidiary?
Not necessarily.
There is no general rule in the current RBI APR framework saying that an auditor performing the relevant certification must physically operate from the foreign subsidiary's country simply because the subsidiary is located there.
What matters is who is legally responsible for the audit or certification and whether the required professional standards and regulatory requirements are satisfied.
This becomes particularly important when companies use:
A local foreign auditor for statutory accounts;
An Indian chartered accountant for APR-related certification;
A global audit network coordinating both teams; or
A combination of local and Indian professionals.
Companies should clearly define each professional's role rather than assuming that one auditor's report automatically satisfies every Indian reporting requirement.
How a Hybrid Audit Often Works Best
For multinational groups, the most practical model is often neither completely remote nor completely physical.
A hybrid process might look like this:
Step 1: The overseas statutory auditor completes the local financial statement audit.
Step 2: The Indian finance team collects the audited accounts and ODI documentation.
Step 3: The Indian auditor or chartered accountant reviews the information relevant to the APR.
Step 4: Questions are handled through video calls and secure electronic document exchange.
Step 5: Physical verification is performed only where the auditor determines that remote evidence is insufficient.
Step 6: The APR is finalised and submitted through the designated AD bank within the applicable timeline.
This approach avoids unnecessary travel while preserving the ability to perform physical procedures where the evidence requires them.
How Companies Can Make APR Filing Faster
The biggest improvement usually comes from preparation, not from choosing between virtual and physical auditing.
Create an annual APR compliance checklist several months before the filing deadline.
At minimum, track:
Foreign entity name and country
ODI reference details
Ownership percentage
Control status
Financial year-end
Audit requirement in the host country
Availability of audited financial statements
Step-down subsidiaries
Changes in shareholding
Additional investment during the year
Loans and guarantees
Previous APR submission
AD bank correspondence
Required certification
Filing status
This effectively turns subsidiary compliance reporting into a recurring process rather than a last-minute finance exercise.
What About Late or Incorrect APR Filing?
Companies should not treat APR reporting as optional simply because the overseas subsidiary has performed poorly or has limited activity.
The current overseas investment framework provides a mechanism for delayed reporting through a Late Submission Fee (LSF) in applicable circumstances. RBI's framework also allows online processing and payment of LSF for relevant overseas investment reporting delays.
However, a late-filing mechanism should not be treated as a substitute for timely compliance.
A better approach is to identify reporting gaps before the APR deadline and discuss them with the designated AD bank and appropriate professional adviser.
A Practical Remote APR Audit Checklist
Before the auditor begins, the Indian company should be able to answer "yes" to most of these questions:
Do we have the overseas entity's latest financial statements?
Are they audited where required?
If unaudited accounts are being used, do we qualify for the applicable regulatory exception?
Do the ownership percentages match our corporate records?
Have all additional investments been reported?
Have we identified any new or closed step-down subsidiaries?
Have we captured changes in the overseas shareholding structure?
Do the APR figures reconcile with the financial statements?
Have we reviewed previous APR filings for consistency?
Do we have evidence supporting the original overseas investment?
Is our designated AD bank information up to date?
Have we identified any delayed FEMA filings?
Has the appropriate auditor or chartered accountant confirmed the certification requirements?
Can all supporting documents be provided electronically?
Are there any matters that may require physical verification?
If the answer to these questions is yes, there is usually much less reason for an APR exercise to become a logistical problem.
Remote Audit vs. On-Site Audit: What Should Companies Choose?
There is no universal winner.
Factor | Remote / Virtual | On-Site |
Travel cost | Lower | Higher |
Speed | Often faster | Can take longer |
Digital records | Highly suitable | Suitable |
Physical assets | May require additional evidence | Easier to inspect |
Complex operations | Depends on evidence | Often advantageous |
Routine subsidiary | Often practical | May be unnecessary |
Risk-heavy engagement | May need hybrid procedures | Can provide stronger physical evidence |
Final Thoughts
A remote audit can generally be compatible with the RBI's APR framework because the regulations focus on the financial statements, certification and reporting requirements, rather than imposing a blanket physical-presence requirement on auditors. The current framework expressly contemplates audited financial statements as the basis for the APR and provides a certification route for qualifying cases where statutory audit is not applicable.
For companies managing overseas investment compliance, the more important task is therefore not arranging an auditor's flight. It is making sure the underlying records, ownership information, financial statements and FEMA reporting are accurate and internally consistent.
A well-prepared remote audit can be efficient. A poorly prepared remote audit can become a long exchange of missing documents and follow-up questions.
The best approach is usually to start the APR process early, coordinate the overseas statutory auditor with the Indian finance and compliance team, maintain a clear subsidiary compliance reporting file throughout the year, and involve the designated AD bank where interpretation or reporting issues arise.
Ultimately, APR filing in India is a reporting exercise built on evidence. Whether that evidence is collected across a conference call or during an on-site visit is secondary to whether it is reliable, complete and sufficient for the professional responsible for the audit or certification.