Which Countries Don't Require a Statutory Audit? A Country-Wise Table for APR Filers
Compare country-wise audit exemptions and understand when controlled foreign subsidiaries still need an APR audit under India's ODI compliance rules.

Accorp Compliance Team
Our team of compliance experts specializes in PCI DSS, SOC 2, and other security frameworks to help businesses achieve and maintain compliance.
"Our subsidiary is audit-exempt in that country, so there's nothing to audit for the APR." AD banks hear some version of this every autumn, and it is right about half the time. The exemption is real in many places, but under India's overseas investment compliance rules it answers only one of two questions. The second question usually decides the outcome.
The two tests behind every APR audit decision
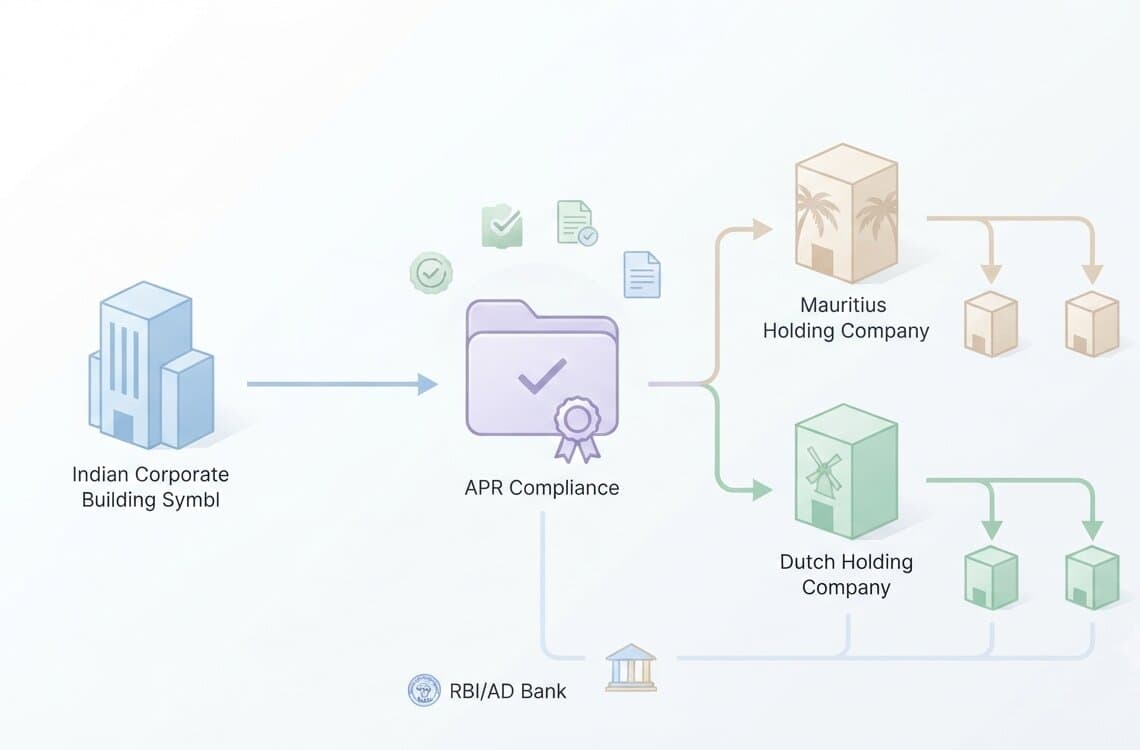
Regulation 10(4) of the Overseas Investment Regulations, 2022 says the Annual Performance Report is based on the foreign entity's audited financial statements. It has one carve-out. Unaudited statements can be used only if both conditions hold:
The Indian investor has no control over the foreign entity.
The host country's law does not require its accounts to be audited.
In that case, the Indian entity's statutory auditor, or a chartered accountant where there is no statutory auditor, signs off on the unaudited figures.
Two things follow. First, a country's audit exemption helps you only if you also lack control. The rules look at the right to appoint a majority of directors or to control management or policy decisions, so a wholly owned subsidiary is controlled by definition. Our note on what counts as control covers the borderline cases. Second, "no statutory audit" is a statement about one country's company law, and the answer often changes with entity type, size and group membership.
Treat the table below as the answer to the first test only. For a controlled entity, FEMA compliance still calls for an audit even where local law asks for nothing.
Country-wise table: private subsidiaries, September 2026
Country | Statutory audit position for a small private company | Watch-out for APR filing |
United States | No general statute requires private companies to be audited. Audits usually come from lenders, investors or contracts. | Control decides everything. A controlled LLC or C-Corp still needs an audit for the APR. |
United Kingdom | Exempt if two of three are met: turnover up to £15m, balance sheet up to £7.5m, up to 50 employees (years starting on or after 6 April 2025). | Group tests apply, and members holding 10% or more can demand an audit. |
Ireland | Exempt on two of three: turnover up to €15m, balance sheet up to €7.5m, up to 50 employees (years from 1 July 2024). | Late annual-return filing can forfeit the exemption. |
Singapore | Private companies meeting two of three for two consecutive years: revenue up to S10m,assetsuptoS10m, up to 50 employees. | Subsidiaries must also pass the group test. ACRA announced a review of thresholds in February 2026. |
Hong Kong | No exemption. Every active company is audited by a practising CPA. | Only formally dormant companies escape the audit. |
Australia | Small proprietary companies are generally exempt. | Foreign-controlled small companies must lodge audited accounts unless ASIC relief applies. |
UAE | Mainland LLCs must be audited. Free zone rules depend on the zone authority. | Audits become mandatory for tax purposes for Qualifying Free Zone Persons and above AED 50m revenue. |
Canada | A non-distributing corporation may waive its auditor by a resolution of all shareholders. | The waiver lapses at the next annual meeting, so it must be renewed every year. |
Traps behind the table
Four rows have a headline rule that differs from the real one.
Australia: an exemption foreign owners don't get. A small proprietary company is generally exempt from audit, but not when a foreign company controls it, which describes an Indian-owned Pty Ltd. ASIC relief exists but comes with conditions. Even where relief applies, it does not answer the APR question, which Regulation 10(4) governs.
The UAE's free zone patchwork. Mainland LLCs are audited annually under Federal Law No. 32 of 2021, whatever their size. Some free zone authorities, such as DMCC and JAFZA, require audits regardless of revenue. A small entity in another zone may have no local audit duty until it becomes a Qualifying Free Zone Person or crosses AED 50 million in revenue, and then Ministerial Decision 84 of 2025 requires audited statements for tax purposes. Check your zone's rules and your tax status separately.
Hong Kong: no threshold at all. Small private companies qualify for simplified reporting, but the reporting concession is not an audit exemption. A Hong Kong company with almost no turnover is still audited by a practising CPA.
Thresholds that keep moving. The UK raised its limits for years starting on or after 6 April 2025, and Ireland did so from July 2024. A subsidiary that needed an audit last year may not need one this year, so check every year rather than copying last year's file.
What "no statutory audit" still leaves you with
Once the host country asks for nothing, the two remaining paths look very different for RBI reporting requirements.
Path one: no control and no local audit mandate. Unaudited statements can support the APR, with the sign-off described above. Several banks expect the Indian company's board to approve those accounts. Keep a short note on file showing that both conditions were checked, because the bank may ask.
Path two: control, but no local audit mandate. This is the common case for wholly owned subsidiaries. An audit is required, and who may sign it is the open question. Some AD banks accept an Indian chartered accountant's special-purpose audit where the host country has no audit mandate. Others insist on a locally licensed auditor. We explain the conflict for UK entities in our note on the UK small-company exemption versus RBI's audit expectation. Ask your bank for its position in writing before you engage anyone.
A worked example
Take an Indian software company that owns 100% of a Singapore private company. The subsidiary has S3 million in revenue, S2 million in assets, and 12 staff, so it is a small company and exempt from audit under Singapore law. The first test passes.
The second test fails. A 100% shareholder has control, so the APR still needs audited statements. Singapore's exemption relieves the company of a local audit, and the Indian parent's reporting duty remains. If the year closed on 31 March 2026, the APR falls due on 31 December 2026. Overseas auditors need several weeks, so the appointment should happen in the next few weeks.
Now change the facts. The same company holds 12% of a Dubai free zone start-up, with no board seat and no management rights. If the zone asks for no audit and the start-up has not become a Qualifying Free Zone Person, both conditions are met, and the unaudited route is open. Which side of that line a holding falls on is the first thing we check for a new client's subsidiary list at our APR audit desk.
The exemption belongs to the country, but the audit duty belongs to the investor.