APR Audit for Indian-Owned UK Ltd Companies: What's Required
APR filing India for UK subsidiaries: Understand audit exemptions, FRS 102, group status, Registered Auditors, and documents needed for RBI compliance.

Accorp Compliance Team
Our team of compliance experts specializes in PCI DSS, SOC 2, and other security frameworks to help businesses achieve and maintain compliance.
When an Indian company sets up a Joint Venture or Wholly Owned Subsidiary in the UK, the annual compliance obligations run on two separate tracks — UK company law on one side, and India's RBI reporting requirements on the other. Getting the APR filed correctly depends on understanding exactly where these two tracks connect, and what documentation from the UK side actually satisfies India's certification requirements.
This article lays out what's specifically required for an Indian-owned UK Ltd company to complete its annual overseas subsidiary audit and support a clean APR filing India.
Why UK Companies Don't Follow a Single Audit Path
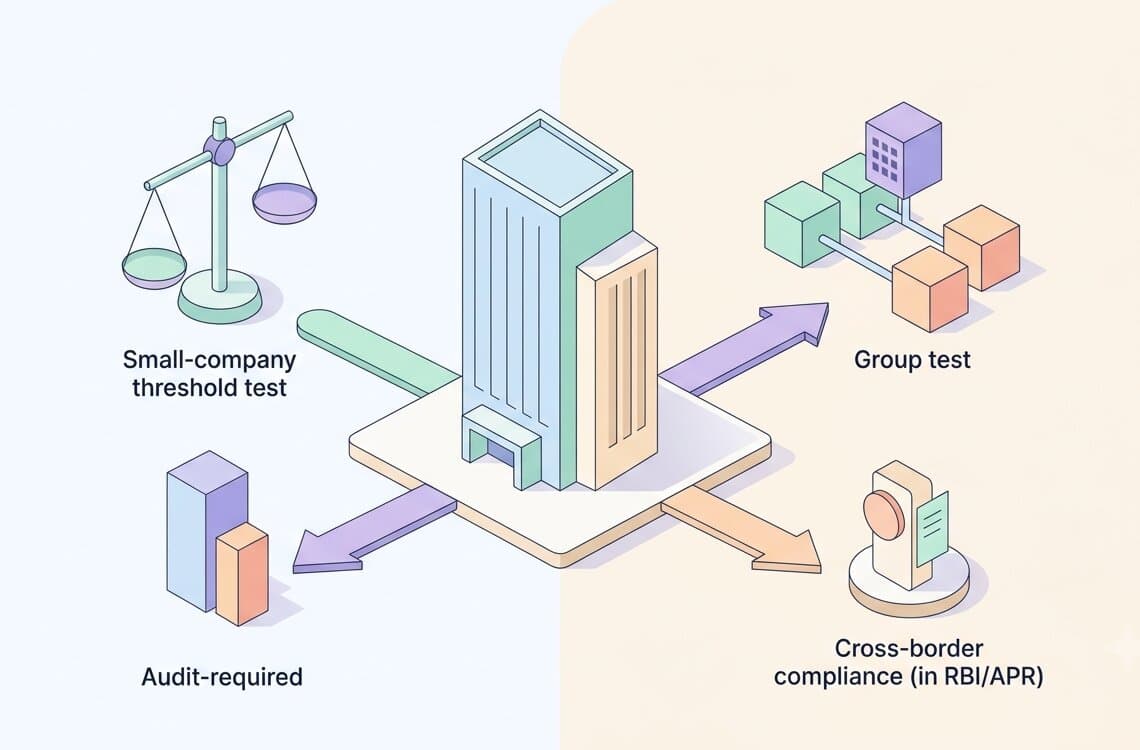
Unlike some jurisdictions where audit is mandatory regardless of size, UK company law applies a tiered system. Whether a UK Ltd company needs a statutory audit at all depends on its classification under the Companies Act — a distinction that shapes the entire foreign subsidiary audit compliance process for the year.
This means the first question for any Indian-owned UK entity isn't simply "who audits it," but "does this company require a statutory audit in the first place, and if not, what takes its place?"
Determining the UK Entity's Size Classification
UK companies are classified based on turnover, balance sheet total, and employee numbers, generally assessed over two consecutive financial years. Companies falling under the small company thresholds can prepare accounts under FRS 102's reduced-disclosure regime and, in many cases, qualify for audit exemption. Larger companies fall outside this exemption and require a full statutory audit.
Because these thresholds have periodically been revised, it's worth confirming the applicable figures for the relevant financial year with the UK auditor for APR filing, rather than assuming the same classification applies indefinitely.
Why Group Status Can Change the Picture
A UK subsidiary that appears small when assessed on its own may not qualify for exemption once its position within a larger group is considered — particularly where that group includes an Indian parent with its own consolidated financial position. This group-level consideration is one of the most commonly missed details in overseas investment compliance, since businesses often evaluate the UK entity in isolation without checking whether group thresholds change the outcome.
Who Is Authorised to Conduct the UK Audit
Where a statutory audit is required, it must be carried out by a Registered Auditor under the Companies Act 2006 — an individual or firm that holds an appropriate audit qualification and is registered with a Recognised Supervisory Body such as ICAEW, ICAS, or ACCA. Not every chartered accountant in the UK is automatically eligible to sign a statutory audit report; audit rights require a separate qualification beyond general accountancy membership.
This distinction matters for Indian businesses coordinating with their UK CPA for APR filing, since confirming that the professional engaged actually holds registered auditor status avoids later complications when the Statutory Auditor in India reviews the certification.
What the Audit Actually Covers
When a full statutory audit applies, the UK auditor reviews the subsidiary's financial statements — prepared under FRS 102 — and forms an opinion on whether they give a true and fair view of the company's financial position. This includes verifying:
Revenue, expenses, and overall profit or loss for the year
Assets and liabilities, forming the basis of the entity's net worth
Related party transactions, including amounts owed to or from the Indian parent
Consistency with the prior year's closing figures
This audited output becomes the primary document the Statutory Auditor in India relies on to certify Form ODI Part II.
What Happens When the Entity Is Audit-Exempt
Many smaller Indian-owned UK subsidiaries qualify for audit exemption. In this case, the company still prepares financial statements under FRS 102, typically using the reduced disclosures available under Section 1A, but without a formal audit opinion attached.
For ODI compliance purposes, this is not treated as a compliance gap — it simply means the Statutory Auditor's certification in India is based on unaudited but properly prepared FRS 102 accounts, along with clear documentation confirming the entity's exemption status under UK law.
Documentation Needed for the APR
Regardless of whether the UK entity was audited or exempt, certain information needs to be available to support subsidiary compliance reporting:
FRS 102-compliant financial statements for the relevant year
Confirmation of audit status — full audit, or exemption with supporting basis
Details of dividends, fees, or other amounts due to the Indian parent, and confirmation of repatriation within the prescribed timeframe under FEMA compliance requirements
Records of any investment movement, including additional capital or disinvestment during the year
Reconciliation between the current year's opening position and the prior year's closing figures reported in the previous APR
Coordinating UK Timelines With RBI's Deadline
UK companies typically file their accounts with Companies House within nine months of their financial year-end, which doesn't always align with India's December 31 APR deadline. Businesses need to map out when the UK entity's financial statements will realistically be finalised — audited or exempt — and build in enough time afterwards for reconciliation and Statutory Auditor certification in India.
This becomes especially important for companies also managing entities in other jurisdictions, since a UK subsidiary's audit cycle can run on a very different timeline from a US CPA for APR filing working on a US entity, or an auditor handling a Singapore Pte Ltd.
Common Issues Specific to UK Entities
A few recurring problems show up when Indian parents manage APR filing for foreign subsidiaries with a UK Ltd company:
Assuming any UK accountant can sign a statutory audit. Audit rights require Registered Auditor status, not just general chartered accountancy membership.
Missing group-level reclassification. A UK subsidiary that looks small standalone may not remain exempt once assessed with its Indian parent's consolidated figures.
Treating threshold changes as static. UK size thresholds have been revised periodically, and using outdated figures can lead to an incorrect exemption assessment.
Why This Matters for Broader Compliance Management
For Indian businesses managing multiple overseas entities as part of a wider international business compliance framework, understanding the UK's specific classification and audit-qualification rules prevents the common mistake of applying a one-size-fits-all approach across jurisdictions that each work quite differently.
Conclusion
An APR audit for an Indian-owned UK Ltd company depends entirely on the entity's size classification, its group status, and whether it falls under the UK's audit exemption rules. Confirming these details early, engaging a properly qualified Registered Auditor where required, and preparing the right documentation regardless of audit status is what keeps annual compliance for foreign subsidiaries accurate and the overall APR audit process free of last-minute correction.