Filing Your Final APR: What Happens to the Audit When You Divest
Understand ODI divestment compliance, final APR audits, Form FC, 90-day repatriation, disinvestment reporting, and UIN closure requirements.

Accorp Compliance Team
Our team of compliance experts specializes in PCI DSS, SOC 2, and other security frameworks to help businesses achieve and maintain compliance.
Companies planning to exit an overseas subsidiary usually focus on the commercial side of the transaction — valuation, buyer negotiations, tax structuring — and treat the RBI reporting side as an afterthought that gets handled once the deal closes. This is one of the more expensive assumptions in ODI compliance. Divestment doesn't quietly end your reporting relationship with RBI. It has its own filing requirement, its own timeline, and its own audit question that has to be answered before the exit is actually complete from a FEMA standpoint.
Why Divestment Doesn't Automatically Close Your APR Obligation
The instinct many finance teams follow is straightforward: once the shares are sold and the money's moved, the compliance chapter on that foreign entity closes with it. RBI's framework doesn't work that way. The Annual Performance Report obligation runs for as long as the Indian party holds equity in the foreign entity — which means the year in which you divest is still a year that needs to be accounted for, not skipped because the entity no longer exists on your books by year-end.
RBI's own enforcement history makes this a genuinely recurring problem. Compounding orders repeatedly show companies disinvesting from an overseas entity while the APR for that stretch of the year was never filed at all — not delayed, simply never submitted, because the exit was treated as the end of the obligation rather than a trigger for one final piece of reporting.
The Final Year: Does the Divestment-Year Entity Still Need an Audit?
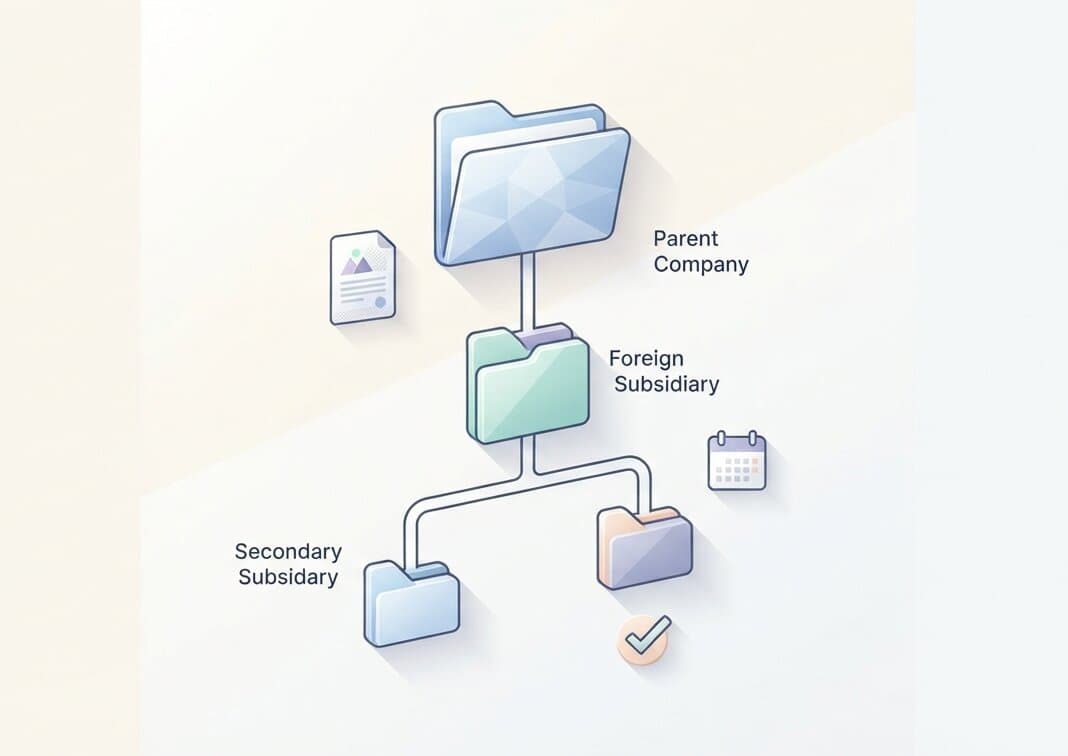
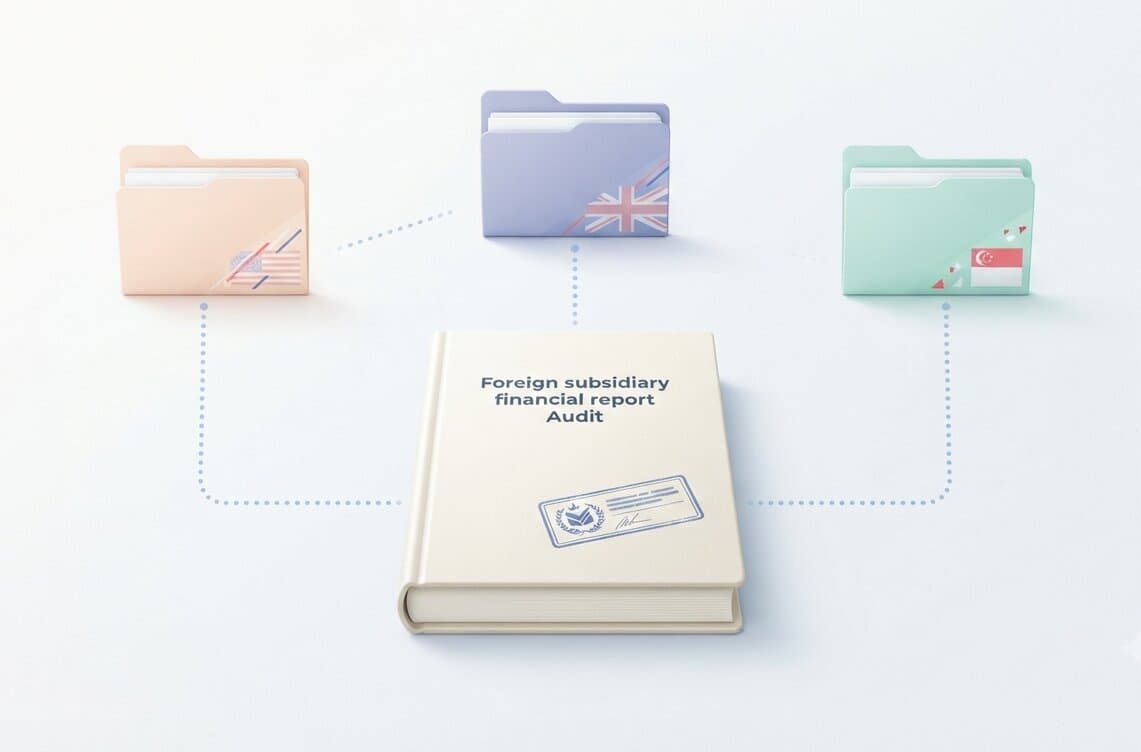
This is the specific question this piece exists to answer, and the honest answer is: usually yes, for the period that matters. Where a full financial year has elapsed since your last APR and the divestment date, that intervening period typically still needs to be accounted for through audited or certified financials, following the same jurisdiction-specific rules that applied throughout the investment's life — a licensed CPA for a US entity, an ICAEW or ACCA member for a UK one, an ISCA-registered accountant for Singapore.
Where the gap between your last filed APR and the disinvestment date is shorter — a matter of months rather than a full accounting year — RBI's own Form APR instructions carve out a more practical path: transactions undertaken between the date of your last submitted APR and the date of disinvestment or initiation of liquidation can be reported through Form FC instead of requiring a fresh standalone APR audit for that stub period. This distinction matters enormously for planning purposes, because it changes whether you need to commission a full audit engagement for a partial year or whether a simpler transactional filing covers the gap.
Reporting the Stub Period: Form FC vs a Full APR
Getting this distinction right avoids two opposite mistakes. Some companies over-comply, commissioning a full audit for a three-month stub period when Form FC would have sufficiently captured the intervening activity. Others under-comply, assuming that because the entity is being wound up, no reporting is needed for the current year at all — which is precisely the contravention pattern that shows up repeatedly in RBI's compounding orders.
The practical rule is this: if a full APR was already filed for the most recently completed financial year, and divestment happens partway through the next year, Form FC can typically capture the remaining transactions. If an entire financial year has passed without an APR being filed before divestment occurs, that gap doesn't disappear — it usually still needs to be closed with proper reporting, based on the audited financials for that period, before the disinvestment itself is considered compliant.
The 90-Day Repatriation Clock Running in Parallel
Alongside the reporting obligation, divestment triggers a separate and equally strict timeline: sale proceeds from the disinvestment generally need to be repatriated to India within 90 days of the transaction. RBI's compounding orders show this requirement gets missed almost as often as the final APR itself — companies focus on getting the deal reported and the shares transferred, and the repatriation clock quietly runs out while funds sit in an overseas account waiting for banking formalities that took longer than expected.
These two obligations — the final reporting and the repatriation timeline — often get treated as sequential when they're actually running simultaneously. A company that handles one cleanly but misses the other still ends up with an open compliance item, because RBI's enforcement pattern treats both as separate potential contraventions under the FEMA Overseas Investment framework.
Where Disinvestment Filings Go Wrong in Practic
Looking across RBI's compounding history, a consistent shape emerges: companies that were reasonably diligent about filing APRs during the years they actively held the investment become considerably less diligent in the final year, precisely when the entity is winding down or being sold. The assumption seems to be that an existing entity carries less regulatory weight than an active one. RBI's own enforcement record treats it the opposite way — disinvestment without a corresponding final report, or disinvestment involving amounts repatriated below the original investment without proper documentation, tends to draw more scrutiny, not less, because it represents Indian capital leaving the reporting system at the exact moment oversight should be tightest.
What Actually Closes the UIN
Every ODI investment carries a Unique Identification Number allotted at the time of initial approval, and that UIN doesn't close itself the moment shares change hands. It closes once RBI, through your AD Bank, has received and processed the final disinvestment report along with whatever final-year reporting was required — the completed APR or Form FC covering the period up to exit, confirmation of repatriation within the required window, and the formal disinvestment filing itself. Until that full sequence is acknowledged, the entity technically remains an open compliance item on your ODI record, even after the commercial transaction has fully closed.
Closing Out Cleanly: What to Confirm Before You Consider the Exit Complete
For any company planning to divest from a foreign subsidiary, the compliance checklist runs in parallel with the commercial one, not after it. Confirm whether a full year's audited APR is owed for the period before divestment, or whether the gap since your last filing is short enough for Form FC to cover it. Track the 90-day repatriation window from the date funds are received, independently of how long the disinvestment paperwork itself takes. And treat UIN closure as a formal confirmation to obtain from your AD Bank, not an assumption to make once the deal is commercially done.
The companies that get caught out here aren't usually the ones who ignored FEMA compliance throughout the investment's life — they're the ones who assumed the finish line moved earlier than it actually does. The exit isn't complete until RBI's records say it is, and that last mile is exactly where the discipline built up over years of clean APR filings tends to quietly lapse.