What Does the Auditor's Certificate for APR Actually Have to Say? A Line-by-Line Sample
APR auditor certificate checklist covering FEMA compliance, financial records, ownership documents, funding proof, and key steps for overseas investment reporting.

Accorp Compliance Team
Our team of compliance experts specializes in PCI DSS, SOC 2, and other security frameworks to help businesses achieve and maintain compliance.
For Indian companies that have invested in an overseas joint venture (JV) or wholly owned subsidiary (WOS), the Annual Performance Report (APR) is more than another annual FEMA filing. It is a recurring compliance document that connects the Indian investor's overseas investment records with the financial and operational position of the foreign entity.
One part that often confuses is the auditor's certificate attached to the APR. What exactly is the auditor confirming? Does the auditor certify that the overseas subsidiary is profitable? Are they auditing the foreign companies? What documents do they need before signing?
These questions matter because an APR is submitted through the designated Authorised Dealer (AD) bank, and incomplete reporting can be treated as non-submission under the RBI's current reporting framework.
This guide explains the certificate in practical terms and provides a line-by-line illustrative sample so finance teams, CFOs and compliance professionals know what their auditor is actually being asked to certify.
What Is an APR Under FEMA?
An Annual Performance Report is an annual reporting requirement connected with certain overseas direct investments (ODI) made by persons resident in India.
Where applicable, the Indian investor reports the performance and relevant details of the foreign entity in which it has invested. Under the current OI framework, the APR is generally required for each foreign entity in which the Indian person has made an ODI, subject to specified exceptions. For example, the RBI framework provides an exception where the resident investor holds less than 10% equity without control and has no financial commitment other than that equity investment.
The APR is not simply a financial statement submission. It captures information such as:
The foreign entity's identification details
Changes in capital structure
The investor's percentage holding
Financial performance
Net worth
Dividends and other repatriation
Changes involving subsidiaries or step-down subsidiaries
Other information relevant to the overseas investment
The purpose is essentially to give the RBI a continuing picture of the investment after the original ODI transaction has taken place.
Why Is the Auditor's Certificate Important?
The auditor's certificate provides independent confirmation of information supplied by the Indian investor.
It is particularly important because the APR may rely on the financial statements of the overseas entity. The RBI's framework provides that the APR should generally be based on the audited financial statements of the foreign entity. Where the Indian investor does not control the foreign entity and the host jurisdiction does not require an audit, unaudited financial statements may be used if appropriately certified.
The certificate therefore should not be viewed as a generic "everything is compliant" letter.
The auditor is expected to examine relevant books, records and supporting documents and make the specific certifications required under the applicable APR format.
A Key Point: The Auditor Is Not Auditing the Foreign Subsidiary
This distinction is important.
The Indian statutory auditor does not automatically become the auditor of the overseas subsidiary merely because an APR is being filed.
Instead, the auditor of the Indian investor is dealing with the Indian investor's reporting obligation. They may review the overseas entity's financial statements, investment documents, remittance records and other evidence necessary to verify the APR information and the particular compliance statements being certified.
The extent of work will depend on the facts, the nature of the investment and the certificate required under the applicable reporting form.
That is why companies should not send their auditor only the completed APR spreadsheet at the end of the year and expect a signature.
Line-by-Line Sample of an APR Auditor's Certificate
The following is an illustrative working sample, not a replacement for the prescribed RBI form. The exact wording and fields should be checked against the current RBI reporting form and the designated AD bank's requirements before submission. The current RBI framework requires APR reporting through the designated AD bank, and a CA may certify the APR where statutory audit is not applicable.
1. Identification of the Indian Investor
Illustrative wording:
"We have examined the relevant books of account and records of [Indian Company Name] in connection with the Annual Performance Report for its overseas investment in [Foreign Entity Name] for the year ended [date]."
What this means
This identifies the party whose FEMA compliance is being reviewed.
The auditor should have clarity on:
Legal name of the Indian company
CIN and PAN
Accounting year
Foreign entity involved
Relevant overseas investment records
The name should match the company's statutory and FEMA records exactly. A mismatch between the entity name in the APR and the name appearing in RBI or AD bank records can create avoidable questions.
2. Identification of the Foreign JV or WOS
The certificate should identify the foreign entity to which the APR relates.
This generally includes:
Name of the foreign entity
Country of incorporation
Nature of entity
RBI UIN or other relevant identification reference
Whether it is a JV, WOS or another qualifying foreign entity
The UIN is particularly important because it links the current APR with the historical overseas investment record.
3. Basis of the Financial Information
A critical part of the certificate concerns the financial statements used to prepare the APR.
An appropriate certification may state, in substance, that:
"The APR has been prepared based on the audited financial statements of the foreign entity for the relevant reporting period."
Where an audit is not mandatory in the foreign jurisdiction, and the circumstances satisfy the RBI's conditions, the reporting may instead rely on unaudited financial statements certified in the permitted manner.
Why this matters
The finance team should maintain the foreign subsidiary's:
Audited financial statements
Unaudited financial statements, where permitted
Auditor's report
Accounting period details
Currency conversion workings
Management accounts, where relevant
The figures in the APR should reconcile to the underlying financial information.
4. Capital Structure and Shareholding
The APR contains information about the capital structure and the investor's holding.
The auditor should have sufficient evidence to understand whether the reported ownership percentage is correct.
Supporting documents can include:
Share certificates
Share registers
Subscription agreements
Subsequent share issue records
Transfer documents
Board resolutions
Previous APRs
Foreign entity corporate records
This is especially important where additional investment, dilution, restructuring or a new investor entered the overseas entity during the year.
5. Net Profit or Loss
The financial performance section normally captures the foreign entity's net profit or loss.
The auditor's work here is primarily about whether the figure reported in the APR can be supported by the financial statements used as its basis.
For example, if the foreign entity reports a loss, the APR should not accidentally present it as a positive number because of a spreadsheet formula or currency conversion error.
The historical APR format specifically requires losses to be presented appropriately, including the use of brackets where applicable.
6. Net Worth
Net worth is another important financial indicator.
The auditor should reconcile the reported amount to the relevant financial statements and ensure the accounting period is consistent with the APR.
This becomes particularly useful when the overseas entity has:
Accumulated losses
Fresh capital
Significant retained earnings
Restructured share capital
Material foreign exchange movements
A sudden change in net worth should be explainable from the underlying accounts.
7. Dividend and Other Repatriation
The certificate may also involve verification of amounts received or receivable from the foreign entity, depending on the applicable reporting requirements and form.
This can include:
Dividends
Royalties
Technical know-how fees
Consultancy fees
Other permitted receipts
Older APR documentation specifically contemplated verification of repatriation and supporting bank documentation.
The practical lesson is straightforward: maintain the relevant inward remittance evidence rather than trying to reconstruct it when the APR is due.
8. Compliance With Overseas Investment Rules
This is the section that makes the auditor's certificate particularly significant from a FEMA compliance perspective.
The auditor may be required to certify specific matters concerning the Indian investor's overseas investment, depending on the applicable reporting form and transaction.
For example, the current RBI Form FC certificate for certain overseas investment reporting includes certifications concerning compliance with the OI Rules and Regulations, applicable investment restrictions, required NOCs, financial commitment limits, valuation/pricing requirements, financial-services conditions where relevant, and outstanding reporting delays.
This demonstrates an important principle: the certificate is not merely confirming that the numbers "look right."
It can involve confirmation of specific regulatory conditions.
9. Pending Reporting or Delays
The auditor should also consider whether there are unresolved reporting issues connected with the overseas investment.
This can include delayed:
ODI reporting
APR filings
Changes in shareholding
Step-down subsidiary reporting
Other prescribed FEMA submissions
The current RBI framework provides a Late Submission Fee mechanism for certain delayed overseas investment reporting.
A company should therefore maintain a FEMA compliance tracker throughout the year rather than discovering an old reporting gap immediately before the APR deadline.
10. Signature, Registration Details and UDIN
The certificate should conclude with the auditor's professional identification details.
Depending on the applicable form, this may include:
Auditor's signature
Name of audit firm
Firm registration number
UDIN
Place
Date
Stamp/seal where required
Contact details
Current RBI reporting forms specifically include auditor identification details such as the firm's registration number and UDIN in relevant certificates.
This section should never be treated as an administrative afterthought.
What Documents Should You Give the Auditor?
A well-prepared APR audit starts several weeks before the filing date.
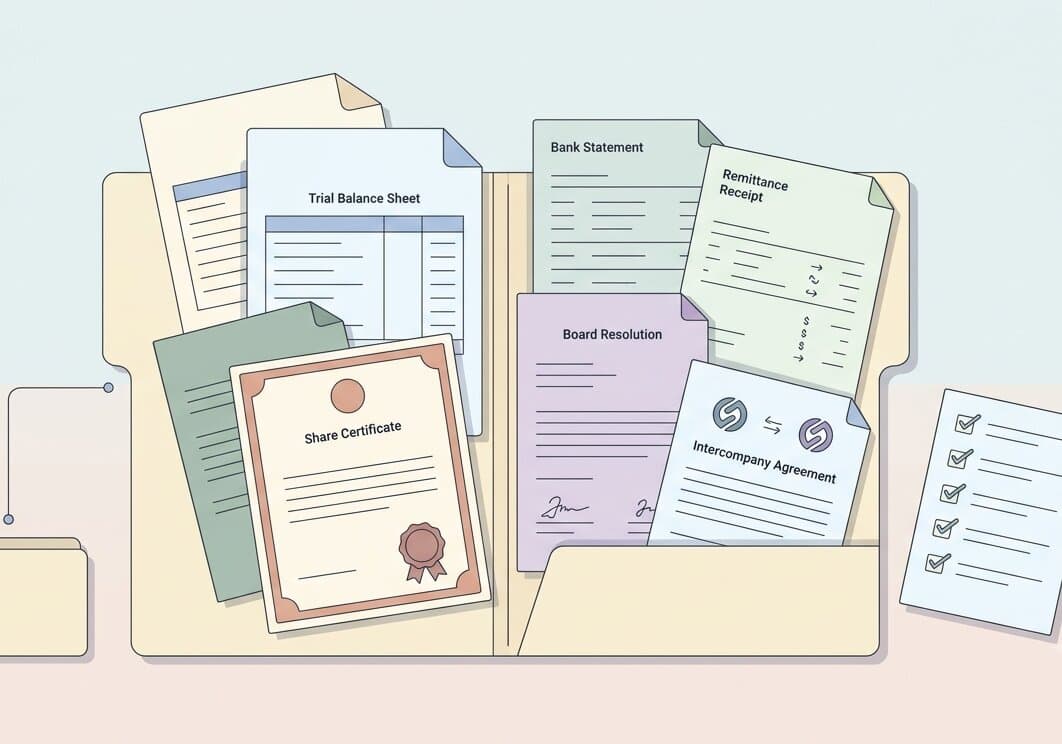
A practical document pack should include:
Corporate Documents
Certificate of incorporation of the foreign entity
Share certificates or equivalent ownership evidence
Updated shareholding structure
JV/WOS constitutional documents
Board resolutions
Previous APR filings
Financial Documents
Audited financial statements of the foreign entity
Profit and loss statement
Balance sheet
Cash-flow information where relevant
Details of dividends
Details of additional capital invested
FEMA and Banking Records
Original ODI reporting records
UIN documentation
AD bank correspondence
Remittance records
Foreign inward remittance evidence
Previous FEMA filings
Details of any delayed reporting or LSF paid
Transaction Documents
Investment agreements
Share subscription documents
Share transfer documents
Valuation reports where applicable
Details of guarantees or other financial commitments
The objective is simple: every material figure and compliance statement in the APR should have a clear source document behind it.
Common Problems That Delay APR Certification
Financial Statements Are Not Finalised
If the foreign entity's accounts are still being prepared, the Indian team may struggle to produce a defensible APR.
Shareholding Has Changed, But Records Have Not
A capital increase or dilution that was never properly reflected in the compliance records can create inconsistencies between the APR and the historical ODI information.
Previous APRs Are Missing
The RBI framework expects continuity in reporting. Companies should verify that earlier APRs have been submitted and recorded with the designated AD bank.
FEMA Transactions Were Not Tracked
A new capital contribution, guarantee, restructuring or step-down subsidiary may have its own reporting implications. Leaving these matters until year-end increases the risk of incomplete reporting.
Currency Conversion Is Inconsistent
Foreign financial statements may be denominated in USD, EUR, GBP or another currency, while internal records may use INR. The conversion methodology should be documented and applied consistently with the relevant reporting requirements.
APR Filing India: A Better Year-Round Process
Instead of treating the APR as a once-a-year compliance exercise, companies with overseas subsidiaries should build it into their regular subsidiary compliance reporting process.
A useful quarterly review can track:
Changes in foreign shareholding
New capital contributions
Dividends received
Guarantees or financial commitments
New step-down subsidiaries
Changes in business activity
Changes in the foreign entity's financial position
FEMA reporting completed during the quarter
Pending AD bank correspondence
Documents required for the next APR
This turns APR preparation into a reconciliation exercise rather than an emergency data-collection project.
APR vs Other FEMA Reporting: Do Not Mix Them Up
One of the biggest sources of confusion is assuming that APR is the only overseas investment compliance requirement.
It isn't.
Depending on the transaction, an Indian company may have other reporting obligations under the overseas investment framework. The RBI's Master Direction on Reporting under FEMA consolidates reporting requirements and emphasises that accurate and timely reporting is important for regulatory supervision.
Similarly, an Indian company with foreign investment into India may have different reporting obligations, such as FLA reporting. That is separate from the APR for an Indian resident's investment outside India.
Understanding this distinction prevents teams from using the wrong compliance checklist.
When Should You Start Preparing the APR?
Ideally, start four to six weeks before the intended filing.
The timeline can look like this:
Week 1: Confirm the foreign entity, UIN, reporting year and applicable APR requirement.
Week 2: Collect financial statements, ownership documents and previous filings.
Week 3: Reconcile financial figures, investment amounts, dividends and shareholding.
Week 4: Auditor reviews supporting documents and identifies gaps.
Week 5: Resolve queries, finalise the APR and obtain the required certification.
Week 6: Submit through the designated AD bank and retain the acknowledgement.
The exact statutory deadline should always be confirmed against the current RBI framework and the company's specific facts rather than relying on an old APR template. The current RBI rules provide specific timing requirements and exceptions, including the 31 December reporting framework for qualifying ODI APRs.
Final Checklist Before the Auditor Signs
Before requesting the certificate, confirm:
Foreign entity financial statements are available.
Shareholding matches corporate records.
UIN and historical ODI records are available.
Previous APRs have been filed.
Dividends and other receipts reconcile to bank records.
New investments and financial commitments have been reviewed.
Step-down subsidiaries have been identified.
FEMA reporting gaps have been investigated.
Currency conversion workings are documented.
Required valuation or supporting certificates are available.
The APR figures reconcile to source documents.
Auditor's certificate wording matches the current applicable RBI form.
Designated AD bank requirements have been checked.
Final Takeaway
The auditor's certificate for an APR is not simply a signature at the bottom of an annual form. It is the point at which the Indian investor's overseas investment compliance, financial records and FEMA reporting trail come together.
For companies managing multiple foreign subsidiaries, JVs or step-down structures, the best approach is to treat APR preparation as part of the broader subsidiary compliance reporting calendar. Maintain ownership records, investment transactions, banking evidence and foreign financial statements throughout the year, and the annual certification becomes significantly easier.
Most importantly, do not use an old sample certificate blindly. RBI's overseas investment framework and reporting forms have evolved, and the applicable certification can depend on the nature of the investment and the reporting circumstances. The current RBI directions should be checked before every filing, with the designated AD bank consulted where the transaction is unusual or historical records are incomplete.