Bank Said You Need an APR Audit? Here's Exactly What That Means
Understand the RBI APR audit for overseas investments, including foreign subsidiary audits, deadlines, requirements, process, and compliance risks.

Accorp Compliance Team
Our team of compliance experts specializes in PCI DSS, SOC 2, and other security frameworks to help businesses achieve and maintain compliance.
Your bank calls you out of nowhere. Or maybe it's an email buried between spam and invoices. "Please submit your APR for FY 2025-26, or your account activity may be restricted." You read it twice. You Google "APR." The first ten results talk about loan interest rates. None of it matches what your bank is asking for.
If this is you right now, take a breath. This isn't a scam, and it isn't something you've done wrong. It's a routine — if often poorly explained — compliance requirement that catches almost every Indian business owner off guard the first time it shows up. Here's what's actually going on, and what to do about it.
First, What Your Bank Actually Means by "APR"
Your bank isn't asking about interest rates. APR here stands for Annual Performance Report — a report the Reserve Bank of India requires every year from any Indian company or individual that has invested in a business outside India.
If your company owns a subsidiary in the US, UK, Singapore, or anywhere else abroad — even a small one, even one that hasn't made any money yet — RBI wants to know how that overseas business performed this year. Your bank isn't inventing this requirement. They're the messenger. RBI holds your Authorised Dealer (AD) Bank responsible for collecting this report from you and passing it along.
Why This Exists in the First Place
India tracks money leaving the country. When your company sent funds abroad to set up or invest in that foreign entity, RBI recorded it. The APR is how RBI checks in every year afterwards — is the investment still active? Is it making money? Losing money? Has anything changed?
Think of it less like paperwork for paperwork's sake, and more like a yearly check-in RBI runs on every rupee that's crossed the border for an overseas investment. Skip it, and RBI has no visibility into whether that money is being used the way it was supposed to be.
Here's the Part That Actually Trips People Up: It's Not Just a Form
Most people assume they can grab a form, fill in some numbers, and send it back to the bank. That's not how this works, and it's the single biggest misunderstanding around APR.
Before you can file anything, the foreign entity's financial statements need to be audited — properly, by a qualified professional in that country. A US subsidiary needs a licensed US CPA to review its books. A UK entity needs a UK-qualified auditor (ICAEW or ACCA). A Singapore entity needs someone certified by ISCA. You can't use your regular Indian CA for this part — the audit has to happen in the country where the subsidiary actually operates, following that country's accounting rules.
This is usually where things get complicated for most companies — finding a CPA in the US, a separate auditor in the UK, and then coordinating between them and your Indian filing, all while managing different time zones and different expectations. It's a genuine pain point, which is part of why Accorp Partners keeps licensed CPA and auditor teams in-house across the US, UK, and Singapore — so the same firm that audits your foreign subsidiary also handles the India-side reporting, instead of you managing two or three separate vendors for one compliance requirement.
Only once the audit is done do you have real, verified numbers to report back to RBI through your bank.
Who Actually Needs to Do This
If any of these describe your company, this applies to you:
You own a wholly-owned subsidiary abroad
You hold a joint venture with a foreign partner
Your Indian company has any active equity investment in a foreign business
And here's the part that surprises people most: it doesn't matter how small or inactive the subsidiary is. A dormant company with zero revenue still needs this. A business that's barely a year old still needs this. The only real exceptions are narrow — mainly cases where your company doesn't control the foreign entity and that country's own law doesn't require an audit at all. For most active subsidiaries, especially anything where you hold a controlling stake, the audit is mandatory, full stop.
What the Actual Process Looks Like
Here's the honest version, not the simplified one:
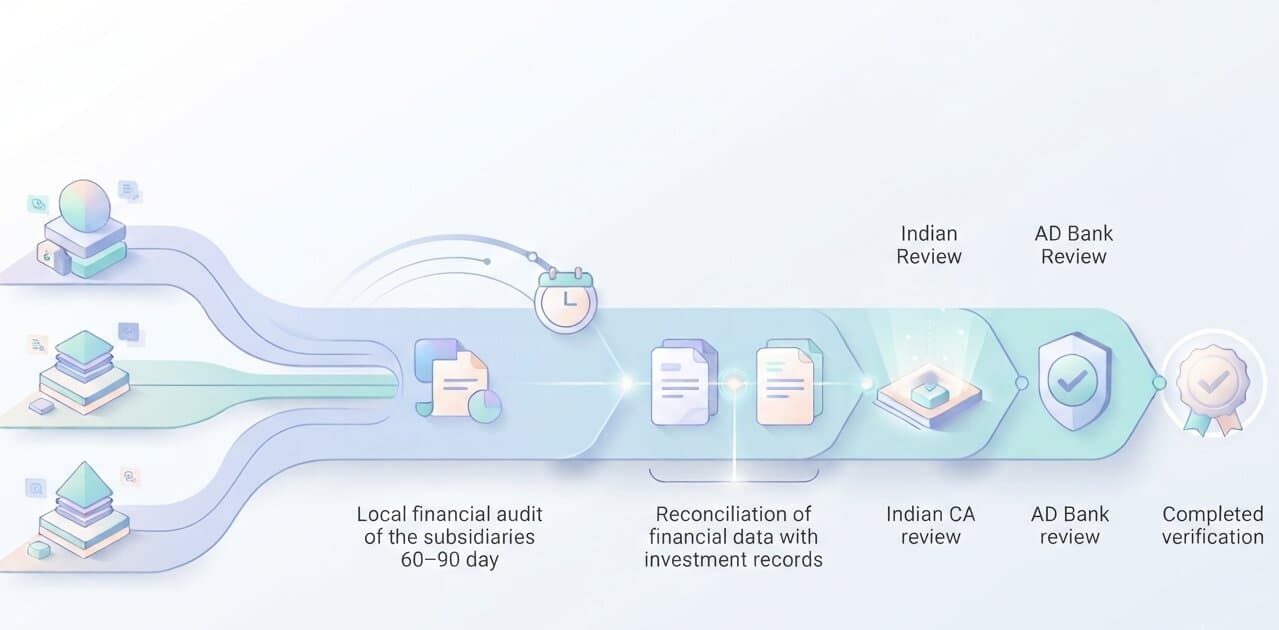
Step one — you (or whoever's helping you) gather the foreign entity's financial records: balance sheet, profit and loss statement, and any supporting documents from the year.
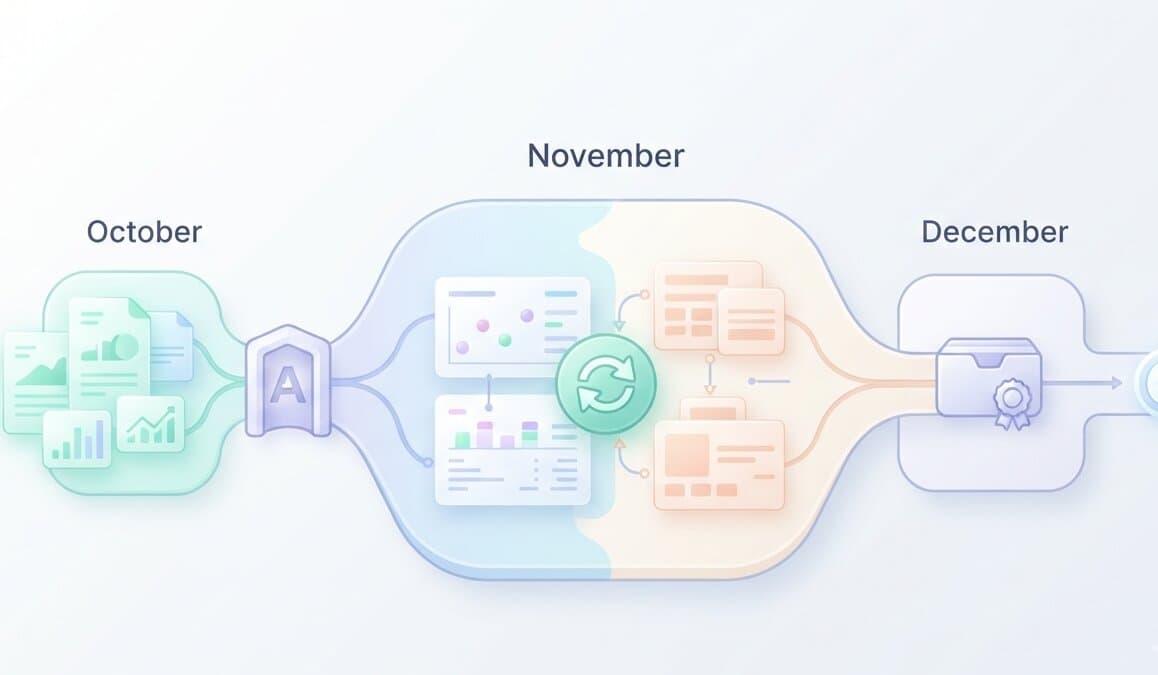
Step two — a qualified auditor in that country reviews the books and issues an audited financial statement. This is the part people underestimate on time. A proper audit engagement usually takes 60 to 90 days, not a week. If you're only starting this in November for a December 31 deadline, you're already behind.
Step three — those audited numbers get reconciled against your original investment records — the amount you invested, your shareholding percentage, any loans or guarantees involved. Small mismatches here are one of the most common reasons banks send documents back with questions.
Step four — everything gets compiled into a proper APR document and submitted to your AD Bank, who reviews it and forwards it to RBI through their FIRMS portal.
How Long Does the Whole Thing Take?
Realistically, from the day you start gathering documents to the day it's submitted, budget two to three months if everything goes smoothly. That's mostly the audit itself — 60 to 90 days — plus time on your end to pull records and answer the auditor's questions. This is exactly why waiting until the deadline is looming is the single most common mistake people make.
What Happens If You Just... Don't
Ignoring the notice doesn't make it go away. Missing the December 31 deadline triggers a late submission fee of ₹7,500. That's the smaller consequence. The bigger one: RBI treats non-filing as a violation under FEMA, and repeated or serious non-compliance can attract penalties running as high as 300% of the investment amount in extreme cases. Your bank may also start restricting further remittances or transactions tied to that overseas entity until you're compliant again.
None of this is designed to scare you — it's just the reality of what "your bank asked for this" actually means if it's left unanswered.
Where This Leaves You
If your bank has flagged this, the clock is already running, and the audit step is the one that actually takes time — not the paperwork at the end. Getting the right auditor engaged early, in the right country, with the right qualifications, is what determines whether this whole process takes two months or turns into a scramble in the last week of December.
If you're not sure where to start, or you just want someone to handle the audit coordination end-to-end instead of chasing a foreign CPA and your bank separately, Accorp Partners runs this process for companies with US, UK, and Singapore subsidiaries — from engaging the right auditor in the right jurisdiction, right through to submission with your AD Bank.
Frequently Asked Questions
1. My subsidiary made no money this year. Do I still need an audit?
Yes. Revenue, profit, or activity level doesn't exempt you. Even a subsidiary with zero transactions for the year still needs its financials audited and reported.
2. Can my Indian CA do this audit instead of a foreign auditor?
Only in specific cases — if you don't have controlling equity in the foreign entity, and that country's own law doesn't require an audit. If you have control (generally 10% or more with decision-making power), the audit needs to happen in the host country by a locally qualified professional, regardless of what Indian law says.
3. What if my subsidiary's financial year doesn't match India's April-March calendar?
This is common with US entities running January-December. RBI allows you to submit unaudited figures initially in this case, with the audited version following within six months of your subsidiary's year-end, or by the following December 31 — whichever comes first.
4. I have subsidiaries in two different countries. Do I file separately for each?
Yes. Each foreign entity needs its own audit and its own APR, even if both fall under the same Indian parent company.
5. What happens after I submit it — is that the end of it?
For this year, yes. But this isn't a one-time requirement. As long as your investment in that foreign entity continues, you'll need to go through this same process every single year by December 31.