UK GAAP/FRS 102 Financials for APR Filing: What RBI Expects
UK GAAP under FRS 102 for APR filing India: Explore size-based reporting, audit exemptions, group tests, and RBI certification requirements for UK subsidiaries.

Accorp Compliance Team
Our team of compliance experts specializes in PCI DSS, SOC 2, and other security frameworks to help businesses achieve and maintain compliance.
When an Indian company holds a UK subsidiary, the financial statements underlying that entity's Annual Performance Report are almost always prepared under UK GAAP, specifically FRS 102. But FRS 102 itself isn't a single, uniform standard — it varies depending on company size, and that variation directly affects what documentation is available for the Statutory Auditor in India to certify. Understanding how FRS 102 applies, and what RBI actually needs from these financials, is essential for accurate APR filing India involving a UK entity.
This article breaks down how UK GAAP financials fit into the APR process and what specifically needs attention before certification.
FRS 102 Isn't One Standard — It's a Tiered Framework
FRS 102 is the primary accounting framework for the majority of UK companies that don't report under IFRS. What makes it different from a single rigid standard is that it includes separate provisions depending on company size — full FRS 102 for larger private companies, and a reduced-disclosure regime under Section 1A for companies that qualify as "small."
For an Indian parent managing overseas subsidiary audit obligations, this means the starting question for a UK entity isn't simply "was it audited under UK GAAP," but "which version of FRS 102 applies, and what does that mean for the level of detail in the financial statements."
Determining Whether the UK Entity Qualifies as Small
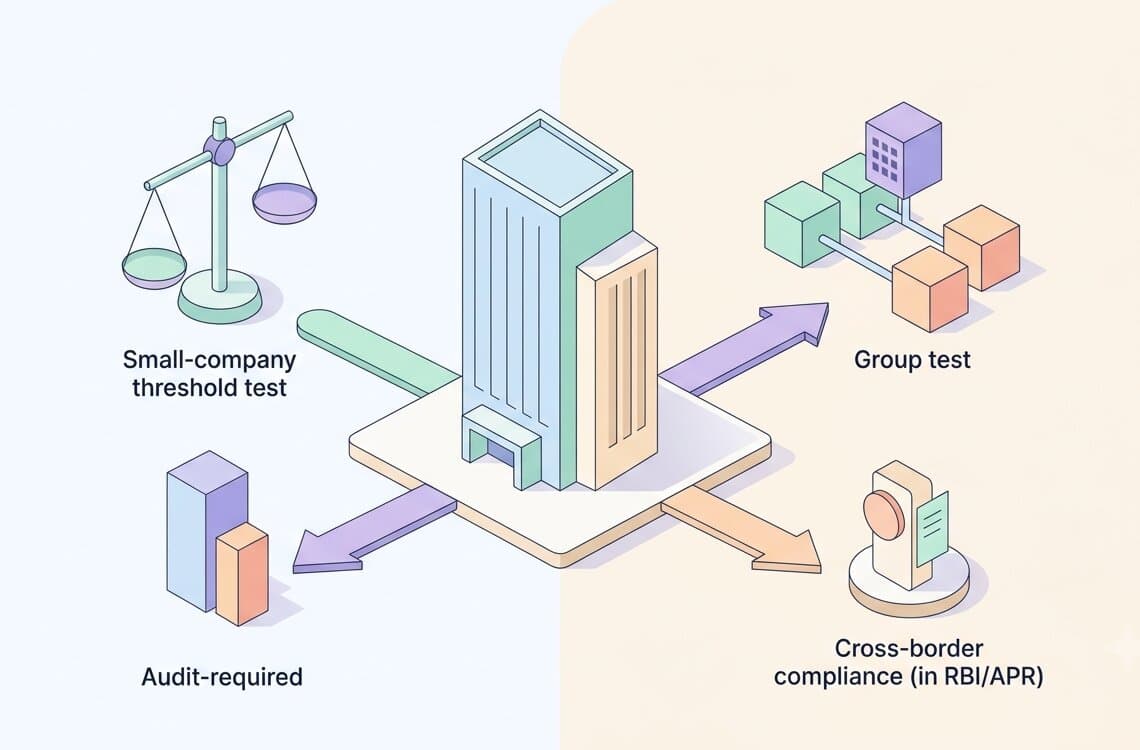
Under the UK Companies Act, a company is classified based on turnover, balance sheet total, and employee numbers, assessed generally over two consecutive financial years. Companies falling under the small company thresholds can apply FRS 102 Section 1A, which allows for significantly reduced disclosures compared to full FRS 102, while still requiring the accounts to show a true and fair view.
This classification matters directly for foreign subsidiary audit compliance, because a small UK entity's financial statements may contain less granular disclosure than what a larger entity would produce — a detail the Indian Statutory Auditor needs to be aware of when reconciling figures against Form ODI Part II.
Why Group Status Affects the UK Subsidiary's Classification
Similar to how group-level tests apply in other jurisdictions, a UK company's eligibility for small company treatment can be affected by its position within a larger group. Where the UK entity is part of a group — including one headed by an Indian parent — group thresholds may need to be considered alongside the entity's standalone figures. This is a detail worth clarifying with the UK auditor for APR filing early on, since it affects both the disclosure level in the accounts and whether the entity qualifies for audit exemption.
Audit Exemption for Small UK Companies
Much like Singapore's small company framework, the UK also permits audit exemption for companies that meet the small company thresholds, subject to certain conditions and exclusions. An audit-exempt UK subsidiary still prepares financial statements under FRS 102, but without a statutory audit opinion attached.
For APR filing for foreign subsidiaries, this means the documentation the Statutory Auditor receives may be unaudited but FRS 102-compliant, rather than a formal audit report. This is a legitimate basis for certification, provided the exemption status is clearly documented and explained rather than left ambiguous, since RBI reporting requirements depend on the Statutory Auditor understanding exactly what level of verification the underlying figures carry.
What RBI Actually Expects From These Financials
Regardless of whether the UK entity was fully audited or fell under the small company exemption, certain elements need to be clearly identifiable within the FRS 102 financial statements to support the APR:
The net worth position of the UK entity, needed to confirm the Indian parent's cumulative investment remains within permitted ODI compliance limits
Profit or loss for the reporting year, reflecting the entity's ongoing operational status
Any dividends, fees, or amounts due to the Indian parent, along with confirmation these were repatriated within prescribed timelines
Investment movement during the year, including any fresh capital or disinvestment
Consistency between the current year's opening balances and the closing figures reported in the prior year's APR
These checkpoints mirror what RBI looks for across every jurisdiction, but the source data for a UK entity comes specifically from its FRS 102 accounts, whether prepared under full disclosure requirements or the reduced Section 1A framework.
Recent Changes to FRS 102 Worth Noting
FRS 102 has undergone periodic review, with updated size thresholds and accounting changes affecting company classification, lease accounting, and revenue recognition applying to accounting periods from specific dates set by the UK government and the Financial Reporting Council. Businesses managing overseas investment compliance for a UK subsidiary should confirm with their UK auditor which version of the thresholds and standard applies for the relevant reporting year, since a company's size classification — and therefore its audit and disclosure obligations — can shift as these changes take effect.
Coordinating FRS 102 Reporting With Indian Certification
Because FRS 102 financial statements aren't automatically structured around what Form ODI Part II requires, coordination between the UK auditor and the Indian Statutory Auditor matters for accurate subsidiary compliance reporting. This includes confirming upfront:
Whether the entity qualifies as small, and what disclosure level that produces
Whether an audit was conducted or the entity relied on exemption
How repatriation of dues and investment movement are captured within the accounts
Whether group-level thresholds affect the entity's classification given its Indian parent
Clarifying these points before the financial statements are finalised prevents the Statutory Auditor from having to request additional detail after the fact, which can compress the certification timeline unnecessarily.
Common Points of Confusion With UK Entities
A few issues recur specifically with UK subsidiaries during APR filing:
Assuming FRS 102 always means a full audit. Many UK entities legitimately rely on audit exemption, and unaudited FRS 102 accounts are a valid basis for certification when properly documented.
Overlooking size reclassification. A UK entity's size category can change year to year, particularly following threshold updates, which affects both disclosure requirements and audit obligations.
Missing group-level considerations. A UK subsidiary that appears small on a standalone basis may not qualify for exemption once assessed alongside the Indian parent's consolidated position.
Why This Matters Across a Multi-Country Portfolio
For Indian businesses managing entities across the US, UK, and other jurisdictions as part of broader international business compliance, recognising that UK GAAP under FRS 102 operates on its own size-based tiers — distinct from how a US CPA for APR filing would approach a US GAAP audit — helps set realistic expectations for what documentation each subsidiary will actually produce.
Conclusion
UK GAAP financials prepared under FRS 102 don't follow a single fixed format — they vary by company size, group status, and whether audit exemption applies. Understanding this tiered structure, and confirming early which version applies to a given UK subsidiary, is what allows the Statutory Auditor in India to certify Form ODI Part II accurately as part of a well-managed APR audit and consistent annual compliance for foreign subsidiaries.