Singapore Chartered Accountant Sign-Off for Form ODI Part II
Understand Singapore CA and Public Accountant roles in APR filing India, audit exemptions, SFRS financials, and Form ODI Part II certification.

Accorp Compliance Team
Our team of compliance experts specializes in PCI DSS, SOC 2, and other security frameworks to help businesses achieve and maintain compliance.
When an Indian company holds a subsidiary in Singapore, the financial statements supporting the Annual Performance Report don't always pass through a formal audit sign-off — Singapore's compliance framework works differently from the US or UK in this respect. Understanding exactly who is qualified to sign off on Singapore-side financials, and what that sign-off actually represents, is essential for getting Form ODI Part II certified without confusion on the Indian side.
This article explains the role of the Singapore Chartered Accountant in this process, how it differs from the Statutory Auditor's role in India, and what businesses need to keep in mind for accurate APR filing India.
Two Distinct Credentials in Singapore's Accounting Framework
Singapore's accounting profession has a structure that's easy to misunderstand from the outside. The "Chartered Accountant of Singapore," or CA (Singapore), is a professional designation conferred by the Institute of Singapore Chartered Accountants (ISCA). Holding this designation confirms a person is a fully qualified accounting professional, but it does not by itself authorise someone to sign a statutory audit report.
To actually conduct audits and sign off on audited financial statements, a CA (Singapore) must additionally register with the Accounting and Corporate Regulatory Authority (ACRA) as a Public Accountant. This distinction matters directly for foreign subsidiary audit compliance, because the professional preparing or reviewing a Singapore entity's accounts may hold the CA (Singapore) designation without being the person legally entitled to issue an audit opinion.
Why This Distinction Matters for APR Certification
For an Indian parent managing overseas investment compliance, this two-tier structure affects what kind of sign-off is actually available from the Singapore side. A CA (Singapore) who is not registered as a Public Accountant can prepare financial statements, review accounts, and support compliance work, but cannot issue a formal audit report. Only a registered Public Accountant can do that.
This becomes especially relevant when the Statutory Auditor in India is trying to determine what level of assurance the Singapore-side documentation actually carries before certifying Form ODI Part II. Confusing a CA (Singapore)'s general sign-off with a Public Accountant's audit opinion can lead to incorrect assumptions about how much verification has actually taken place.
When a Full Audit Applies
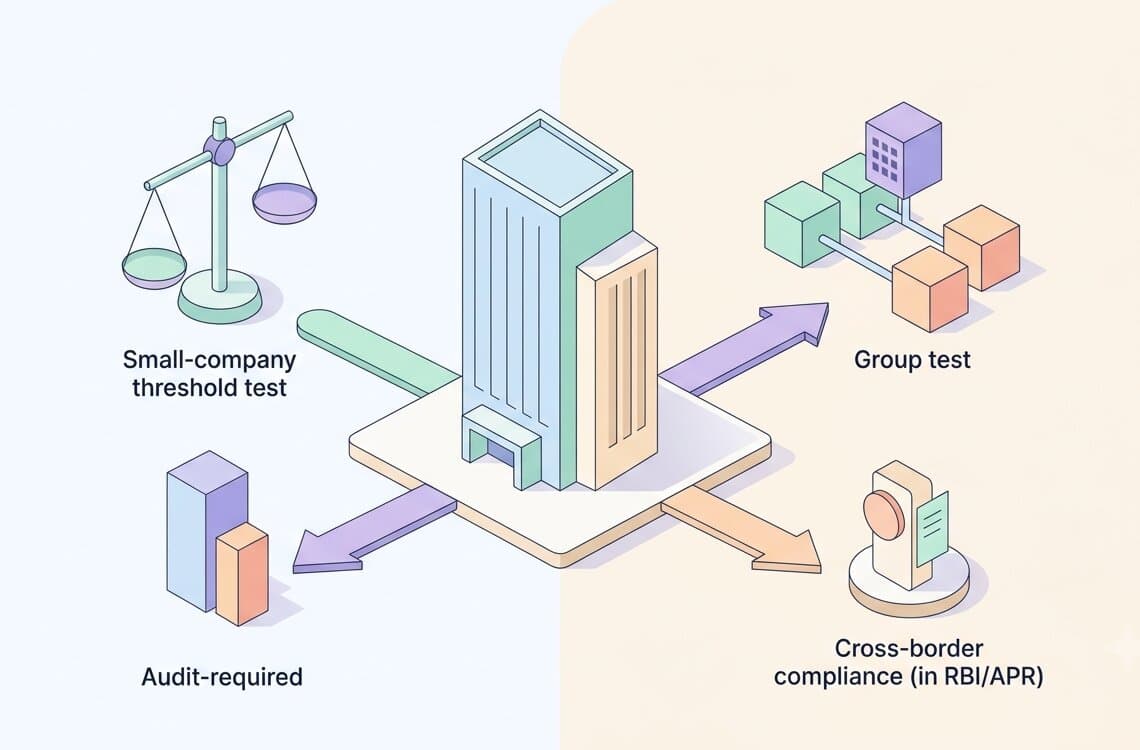
Where the Singapore subsidiary does not qualify for the small company audit exemption — either on its own or because the group test involving the Indian parent's consolidated figures pulls it above the thresholds — a registered Public Accountant must conduct the audit. This is the professional whose sign-off carries the same weight, for RBI's purposes, as a US CPA for APR filing or a UK auditor for APR filing signing off on their respective jurisdictions' financial statements.
In this scenario, the audit report is prepared in line with Singapore Financial Reporting Standards (SFRS), and this becomes the primary document the Indian Statutory Auditor relies on when certifying the APR.
When the Entity Is Audit-Exempt
Many Indian-owned Singapore subsidiaries qualify as small companies and are exempt from mandatory audit. In these cases, there is no Public Accountant sign-off at all — instead, a CA (Singapore), often the company's own accountant or an engaged accounting firm, prepares the financial statements in accordance with SFRS without issuing a formal audit opinion.
This is not a gap in compliance. It reflects Singapore's own regulatory framework, where audit exemption removes only the audit requirement, not the obligation to maintain accurate, properly prepared financial statements. For ODI compliance purposes, what matters is that this exemption status and the basis for it are documented clearly, so the Indian Statutory Auditor can certify accordingly rather than assuming an audit exists where none was required.
What the Statutory Auditor in India Actually Reviews
Regardless of whether a full audit was conducted, the Statutory Auditor's certification of Form ODI Part II depends on understanding exactly what level of verification the Singapore documentation represents. This typically means confirming:
Whether the entity was audited by a registered Public Accountant, or exempt under Singapore's small company rules
Whether the financial statements were prepared in accordance with SFRS
Whether the figures align with what was reported in the previous year's APR
Whether investment movement and any repatriated dues during the year are accurately reflected
This review process supports broader subsidiary compliance reporting obligations and ensures the certification accurately represents what was actually done on the Singapore side, rather than assuming a standard audit process identical to other jurisdictions.
Coordinating Between Singapore and Indian Professionals
Because Singapore's dual structure of CA (Singapore) and Public Accountant registration isn't always familiar to Indian Statutory Auditors, clear communication between the two sides matters more than it might for jurisdictions with a single, uniform audit requirement. It helps to confirm early in the reporting cycle:
Whether the Singapore entity requires an audit this year, based on both standalone and group-level thresholds
Who specifically is preparing or signing the financial statements, and in what capacity
What documentation will be provided to support FEMA compliance requirements tied to the original ODI approval
Clarifying these points before financial statements are finalised avoids last-minute uncertainty about what the Statutory Auditor is actually certifying against.
Common Misunderstandings Worth Avoiding
A few recurring issues show up specifically with Singapore entities during APR filing for foreign subsidiaries:
Assuming any CA (Singapore) sign-off equals an audit. Preparation or review by a Chartered Accountant is not the same as a formal audit opinion unless that person is also a registered Public Accountant.
Overlooking the group test. A Singapore subsidiary that looks small in isolation may still require an audit once assessed alongside the Indian parent's consolidated figures.
Treating exemption as a compliance gap. Audit exemption is a legitimate outcome under Singapore law, not a shortcut, and should be documented as such rather than flagged as missing information.
Why This Matters for Multi-Jurisdiction Compliance
For Indian businesses managing entities across the US, UK, and Singapore as part of broader international business compliance, recognising that each jurisdiction has its own professional structure and audit thresholds is essential. Treating Singapore's framework as identical to the US or UK approach risks either over-requesting documentation that doesn't exist or under-verifying what actually does.
Conclusion
Singapore's split between the CA (Singapore) designation and Public Accountant registration means the sign-off supporting an Indian-owned subsidiary's APR filing can look quite different depending on whether the entity was audited or exempt. Understanding who is actually authorised to issue an audit opinion, confirming exemption status where relevant, and communicating this clearly to the Statutory Auditor in India is what keeps annual compliance for foreign subsidiaries accurate and consistent as part of a well-managed APR audit process.